
American Flag

Best Online Savings & Money Market Account Rates 2026

Best Online Savings & Money Market Account Rates

Recent Articles


JP Morgan Chase Comes to Market with A 7.50% Structured Note

JP Morgan Chase has come to market with the highest yielding 15 year structured note that we have seen in some time. This offering is consistent with the 10 year Treasuries testing of 3.00%, the early stages of some slope to the yield curve, and the increasing governmental scrutiny facing the Jamie Diamond-run's banking behemoth.

I have discussed structured notes at some detail in earlier articles on this site, including this article which was published in 2011 when major banks began offering structured notes again in earnest following the 2008-2009 banking crisis and this article which was published in June 2013 when JP Morgan began to offer its 15 year dual hybrid structured note after a year long period in which long term interest rates were too low for it to fund these operations.

Structured notes are effectively unsecured bank debt with certain conditions that enable the bank to gross up the return that it is offering. Essentially, the bank is selling options against the capital it raises in order to fund a much higher return on the offering than where its unsecured debt might be trading. The return is also higher because the bank has an option to call the note at par quarterly after the first year. In short, I believe that structured notes often represent a good opportunity for investors to pick up yield by taking on negligible risks and I myself generally invest certain amounts of capital in these notes intending to hold them to maturity.

The JP Morgan notes, which it routinely issues and calls Hybrid Range Accrual Notes, only pay interest during those periods in which 6 month LIBOR rates remain between 0 and 6% and the S&P 500 falls by no more than 20% from its level at closing. My June article discussed the risks involved in these contingencies and the real risk that interest might not accrue for long periods while these notes are outstanding.

The most remarkable thing about the latest issue obviously is how much more interest JP Morgan Chase is prepared to give than when it issued the very same notes in June. The June notes, which were identical in term and in conditions, were offered at 6.50% (on closing the price was set at 6.65%). It is now clear that an investor would have been much better served to settle for 0.85% in a savings account for the last 2 and half months than to have locked into a 15 year note that is now trading around 90 cents on the dollar.

In an environment where the 10 year Treasury is now trading close to 3%, but will very likely be trading between 4 and 5% in a year, investors should be very careful before locking into structured notes, just as they should before locking into any bonds in a fast rising interest rate environment. While the opportunity to make 7.50% on a fixed income investment seems very attractive in the current low rate environment, my guess is that JP Morgan Chase and Morgan Stanley will very shortly be offering similar notes with coupons north of 8% and with conditions that are less likely to cause interest payments to be halted (such as a LIBOR period between 0 and 7% or 0 and 8%, instead of 0 to 6%).

Prudent investors will find that rising interest rate environments like this are a good time to hold cash and you will find the best rates on cash by clicking on the savings tab above.

Those seeking more information on this offering can find it under CUSIP 48126D6Z7.

As Long Treasuries Rise, JP Morgan Chase Issues A Structured Notes With a 6.50% Offer

JP Morgan Chase, like Morgan Stanley and Citibank, had exited the structured note market about a year ago when long bonds rates fell so low that structured notes could no longer be structured. Today, they returned to the market today with a new 6.50% structured note.

Brokers at several large investment banks today began syndicating a 6.50% syndicated structured note that will close later this month. The note, which pays quarterly, is conditioned on (a) 6 month US LIBOR being greater than 0 and less than 6%, and (b) the S&P falling by no more than 25% from its close date of June 28, 2013. Interest will not accrue on those days where these conditions are not met. The notes have final maturity in 2028 and are callable in 5 years.

Bank-issued structured notes should not be viewed as an equivalent to placing money in a savings account or even in a CD. They are much more similar to a bond and can fit well in a portfolio designed to generate income with low risk. Ordinarily, structured notes provide much higher yield than you can otherwise obtain on a similar credit. The holder receives the higher coupon as consideration for assuming the risks of the payment conditions.

Under these circumstances, the holder of the notes is prepared to forego interest if the stock market should come down and remain dramatically below its current levels or if 6 month LIBOR were to spike dramatically above current levels.

6 month LIBOR, of course, is not likely to spike from its current exceptionally low levels to a level above 6% at any time in the near future, but it is very likely to head there at some point over the next 15 years. It was consistently above 6% in the late 1980s and early 1990s, and again in 1994 and 1995. It was also intermittently above 6% in 1998, in 1999 and in 2000. It approached but did not cross 6% in June of 2006. In a normalized environment, it could easily get to that level again, and in a very high interest rate environment these notes could easily be rendered free of any obligation for JP Morgan Chase to pay interest for long periods of time.

Therefore, these notes may play a role in a portfolio, but are not an alternative to cash. My advice is that investors put 10-20% of their non-equity liquid asset base that they cannot afford to lose in the highest quality (i.e., JP Morgan issued) structured notes and/or municipal bonds while long term interest rates have spiked up. This will serve as a partial hedge against savings and CD rates continuing at such a low level for a significant, continued period of time.

Those interested in this particular note should search CUSIP 48126DX61/US48126DX615.


Top 10 Least Safe States to Bank

BestCashCow released its list of the Top 10 Least Safe States to Bank. See if your state made the list and what you should do if it has.

Bank failures can be messy for depositors. The bank can be closed over several days, a great rate can be lost, and a depositor can wind up at a bank they never selected. Last week we took a look at the safest states to bank according to the Texas ratio, a widely used number that correlates well with bank failures. Now, we’ll look at the ten states with the least safe banks. The idea is not panic anyone. Even the least safe states have strong insitutions that will not fail. And while everyone should know some basic health stats on where the park their money, this is especially true for depistors in states with banks that are stressed.

To determine our list of least safe states, we generated the average Texas ratio for each state. The Texas ratio measures the amount of capital and reserves a bank has to cover loans gone bad. If a bank can't cover its bad loans, then it is insolvent and will eventually be closed.

The ten banks with the highest Texas ratios (the higher the Texas ratio, the greater the change for bank failure) are:

Ten States with the Least Safe Banks

  1. Georgia
  2. Oklahoma
  3. South Carolina
  4. North Carolina
  5. Florida
  6. Maryland
  7. Illinois
  8. Alabama
  9. Arkansas
  10. Tennessee

To prevent the mega-banks from distorting the state-by-state numbers the analysis only included banks with assets below $10 billion.

As the data shows, six of the ten states came from the South, where rapid population growth in several states increased speculation and led to a lending boom and bust.

Bank Closings

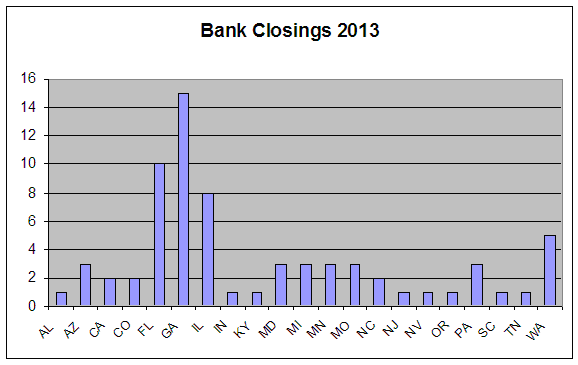
Bank Closings by State in 2013

Now, let's look at how the Texas ratio matches up with some real data. The chart above shows bank closings to-date for 2013. Notice how Georgia, Florida, and Illinois lead the list as predicted by the list. But some of the other states like Oklahoma, Arkansas, and Maryland haven’t seen a single closing so far. The Texas ratio is directional rather than exact and just because a state is on the list, doesn’t mean it will experience drastic bank failures. If you have money deposited in a bank in one of these states, it is especially prudent to check on the health and safety of the institution. Depositors in any state should be on top of the health and safety of where they deposit their money. You can do this on BestCashCow by clicking searching for the bank at the top of the screen and then checking its Financial Details tab (click to view an example for Brookline Bank).

Why does any of this matter with FDIC coverage?

In 2013 alone, thirteen banks have failed through May 14. In the event of a bank failure:

  • Not all deposits are covered. According to the FDIC, up to 20% of deposits in U.S. banks are not covered by FDIC insurance because deposits are over the $250,000 limit. In the event of a bank failure depositors can, and have lost money.
  • Great rates might not be honored. Banks that fail are often acquired by stronger institutions. But these institutions do not need to honor prior CD rates and other terms from the failed bank.
  • It can be inconvenient. While the FDIC generally moves quickly when taking over a failed bank, there can be a several day disruption and lack of access to cash. Depending on the timing this could be a major or minor inconvenience. A depositor of a failed bank may also find themselves a member of another institution that they never chose and prefer not to bank with.

What To Do if Your Bank Has a High Texas Ratio

In general, if you look at a profile on BestCashCow you want your bank’s Texas Ratio to be below 100%. If it’s over 100% then it is an indication that the bank does not have adequate reserves and capital to cover all of its potential losses. A bank’s Texas ratio in excess of 200% is a flashing warning sign. Ideally, your bank would fall somewhere near the national average. If it's below that national average, that's great. You can also look at the Texas ratio trend. Is it going up or down? If up, then your bank maybe accumulating bad loans, not a good sign.

If your bank is above the national average, and especially if its Texas ratio is over 100%, then it would be wise to check that all of your deposits are FDIC insured. Use the FDIC’s deposit insurance tool to make sure you are covered. If you have deposits not insured, move them to another bank so that they are fully insured.