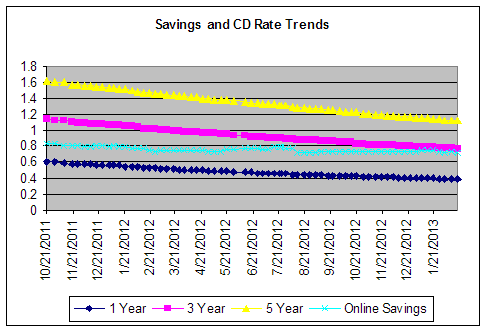
Like the number of days until summer vacation, bank rates continue to decrease, a few basis points today, a few basis points tomorrow. The decline is slow but if you look back, all the little drops add up. Are rates going to 0%. Could we see a 0% 1 year CD average? Probably not but there are some banks that are paying close to 0% for a 1 year CD. My advice, stay away. Shop around. Ther are better rates out there.
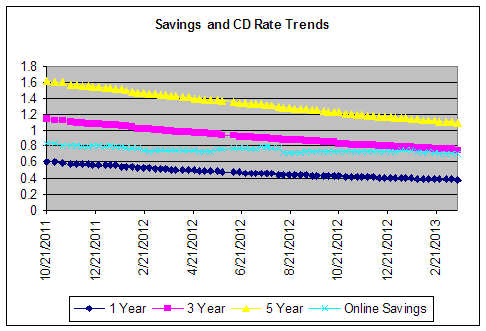
In the last week, average one-year CD Rates dipped from 0.383% to 0.381% APY. Three year average CD rates dropped from 0.757% to .753% APY. Five year average CDs dropped to from 1.107% to 1.100% APY. Online savings rate averages dropped a bit from 0.712% APY to .707% APY after staying steady for three weeks. If the pace of decline continues, we could see 5 year CD rate averages dip below 1% APY sometime in August or September.
Even if the averages are all below 1%, the top rates are still significantly higher. BestCashCow data shows the top rates for some key terms are:
- Online Savings: AmTrust Direct retained the top spot at 1.05% APY.
- 1 Year CD: Five banks retain the top spot at 1.05% APY.
- 3 Year CD: Pentagon Federal Credit Union at 1.60% APY
- 5 Year CD: Barclays Bank Delaware now occupies the top spot alone at 1.85% APY. CIT cut their leading rate from 1.85 to 1.75% APY over the past week.
- Rewards Checking: Hope Credit Union Money One Federal Credit Union both have the top rewards checking rate of 3.01% APY for balances up to $10,000. Both credit unions are open to members from across the country.
Local banks and credit unions often offer better rates (especially for CDs) than online banks so be sure to check them out.
The chart below shows the trend in average rates since October 2012.
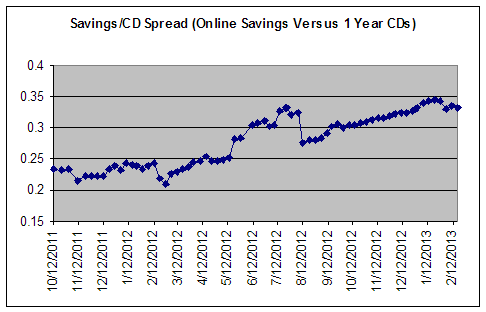
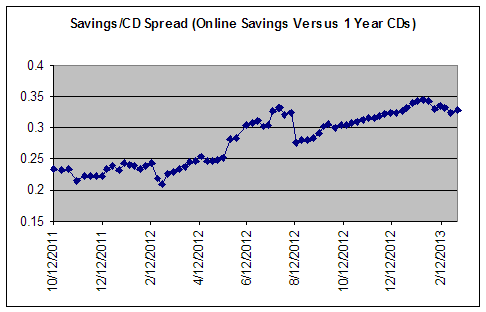
The difference in the rate of decline between online savings and CD rates can be viewed on the chart below, which shows the spread between online savings account rates and 12 month CDs. The spread still remains very elevated although it has come down in recent weeks as several online banks have cut rates. On average, online savings account rates pay .326 percentage points more than 1 year CDs, up from .23 percentage points more at the beginning of last year but down from the spread's high of .344 percentage points in late January.
General rate environment
The U.S. economy continues to chug along. Last week, the Labor Department released the inflation numbers and they looked pretty tame. Inflation increased 0.7 percent in February on a seasonally adjusted basis, the U.S. Bureau of Labor Statistics. Over the last 12 months, the all items index increased 2.0 percent before seasonal adjustment. Most of the increase came from rising gasoline prices. Core CPI, which strips out food and energy, rose .2 percentage points, in line with expectations. Bottom line: No inflation pressure. The Fed still does not need to worry about inflation.
Bloomberg published a very positive housing article. Many economists are expecting big gains in house prices over the next 12 months. JP Morgan Chase expected home prices to increase by 14 percent through 2015. While it's hard to take what bank economists say at face value, some of this data squares with the Case Schiller reports, which show home prices in most U.S. cities on the rise. Housing, which has been a big drag on the economy, now seems to have shifted into a positive contributor.
In his article, "To Reassure Investors, Fed Stresses It Will Not End Stimulus" NY Times reporter BINYAMIN APPELBAUM discusses how the Fed will keep the pedal to the meddle and rates down as long as possible, even if growth accelerates in the next couple of quarters. Most likely, growth will accelerate, but as long as inflation stays below 2%, and uneployment above 6.5%, then rates will continue on their present course.
Europe, Oh Europe
Which bring us to Europe. Just when Europe looked like it was stabilizing and would no longer muck up global growth, they unveil a scheme that has surprised depositors across the world. Cyprus, a tiny economy, has a banking system on the verge of collapse, like in Greece, Portugal, and Ireland before it. Before the EU will agree to give the country a $13 billion bailout needed to keep the banks afloat, it has attached a new and unprecedented requirement. Deposits in Cypriot banks will face a one-time tax to help defray the bailout costs. Deposits of more than 100,000 Euros will face a levy of 9.9% while those under 100,000 Euros will face a levy of 6.75%. In all the previous European bailouts, bondholers and shareholders were forced to take the cut while taxpayers helped to foot the bill. Imagine waking up and finding out that your savings account had been reduced by 10% overnight.
Cyprus does have a deposit guarantee through the central bank but it is worth little if the entire financial system has collapsed and the country has no money. Should Europe pay off depositors? Probably. But this underscores the fact that the deposit guarantee is only as good as the country that backs it. It also underscores why a country with only several large banks can collapse the entire system if they get into trouble.
FDIC and NCUA deposit insurance in the United States appears to be solid. No depositor, including in the Great Depression and the Financial Collapse in 2008, has ever lost a penny of FDIC insured money. But it could still happen one day. That's why BestCashCow provides an indicator of bank health and safety on each bank's page (example: Brookline Bank). A safe bank doesn't mean lower rates either. Our research has shown that banks that are in better fiancial condition, generally offer better rates. Depositors can have their cake and eat it also.
The EU is already backtracking on the Cyprus deposit levy idea, so we'll see where it goes. If the problem spreads and causes bank runs in other countries, then Europe will once again become a drag on U.S. growth and I'll have to extend my outlook for when rates will rise.
My outlook: Savings rates will continue to drift lower for the next 9-15 months before beginning to move higher. How high and how fast they move will depend on the level of local, state, and federal taxes and cuts, ; the continuation of a recent economic uptick; technological advances; and the ability of Europe to put its woes behind it and resolve its fiscal problems.
Savings Accounts or CDs?
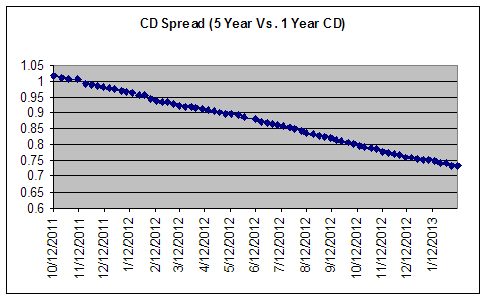
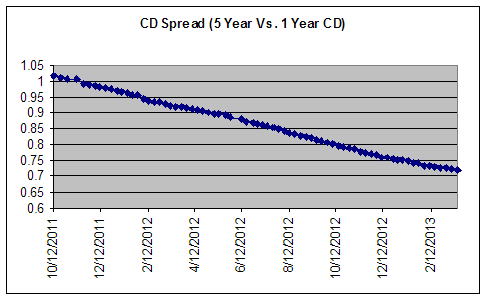
The data continues to show that opening a savings account is a better bet than a 1-3 year term CD and I expect this to hold through 2013. Online savings accounts have held the line over the past year while CD rates continue to fall. As the chart shows, the premium for opening a longer-term CD has eroded significantly and continuously over the past year. While the premium for opening a 5 year CD over a 1 year CD was 1 percentage point in October 2011, it now stands at .728 percentage points.
So for now, here are my recommendations on which deposit accounts to open::
For money you want to keep liquid, go with online savings accounts. They offer better rates than 1-3 year CDs and athough several banks have dropped rates in the past week, they have still offered decent rate stability over the past year.
If you want to take advantage of the higher rates on longer-term CDs, look to open them at local community banks. BestCashCow research has shown that community banks and credit unions offer the most competitive rates on longer-maturity CDs. Otherwise, you'd be better off keeping your money liquid in an online savings account.
I believe this is the best and easiest strategy for keeping your cash liquid and maximizing your savings over the next year.
Make the best of a tough savings situation in 2013
Yields may be low in 2013 but a savvy saver can boost the return with no increase in rate by rate shopping. By shopping around, a saver can earn an extra half to full percentage point. On $100,000, that's $1,000 in extra cash per year. Remember, even in today's environment, there is competition for your cash.