New York

Image Courtesy: pixabay.com

Four Questions That Your Mortgage Lender Will Ask

Meeting with a mortgage lender may seem like an intimidating process. But if you know some of the questions they are going to ask, you can be prepared and less intimidated.

Since buying a home is such a large investment, most buyers need to utilize the services of a mortgage lender to make it happen. But when you borrow money from a lender, they want to make sure they will be getting repaid along with interest. They will ask you many questions before deciding to offer you a mortgage loan. Here are some questions you should expect to answer so you can be prepared with answers and documentation.

1. What is your employment and income status?
Being employed is vital when applying for a mortgage. Your lender is going to want to know many things about your employment status, including where you work, how much you make and how long you have worked there. In addition, they will ask about how you are paid – do you receive salary? Commission? Or hourly wages? Do you have a regular income or is it fairly irregular? Many mortgage lenders will also want to see pay stubs and other income documentation before making their final decision.

2. What debts do you have?
Debt is simply a part of American culture. But if you have too much debt, you are going to have a difficult time finding a mortgage lender to loan you money. Your lender is going to want to know about your auto loan debts, your credit card debts, medical bills, student loans and any other monies that you owe. They will also want to know how much money you have left after making a down payment on the home and paying for closing costs. Bring documentation of your debts and your bank statements when meeting with your lender and don’t try to hide anything. If you do, you could end up with financial problems – or even legal problems - soon after moving into your new home.

3. How much can you put down?
The bigger of a down payment you can put down on a house, the better your chances of getting a home loan. This is especially true if you have questionable credit. When you put a larger down payment on a home, the lender sees that you are financially invested in the home so you become a better credit risk for them. However, they may ask where you got the money from – was it a gift from your parents or did you save up for a few years? This may not have a huge impact on the lender’s decision, but it may still be a factor.

4. What is the purpose of the home?
In most cases, you will be buying a home as a primary residence. However, there are many home buyers who purchase homes as investment properties to rent out or as vacation homes. Your lender is going to want to know what you plan on doing with the home after you buy it so be honest with them about your intentions.

Your mortgage lender is there to help you find a home loan. While they are in the business to make money, they also have a great deal of expertise. If you are honest with them about these and the other questions that they ask, they are in a better position to help you get the mortgage loan.

Compare the best mortgage rates here.

Average 30 Year Fixed Rate Mortgage Drops Below 4% for First Time

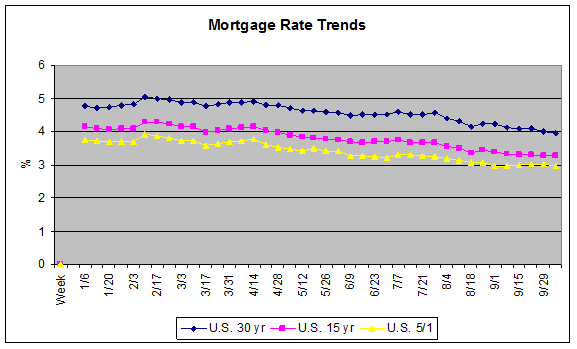
The average thirty year fixed rate mortgage rate dropped below 4% for the first time on record according to Freddie Mac's Weekly Mortgage rate survey. Fifteen year rates and 5/1 ARMs also dropped to record lows as the chart below shows.

The average thirty year fixed rate mortgage rate dropped below 4% for the first time on record according to Freddie Mac's Weekly Mortgage rate survey. Fifteen year rates and 5/1 ARMs also dropped to record lows as the chart below shows. The drop in mortgage rates corresponds to a drop in 10 year Treasury notes.

Mortgage Rates

There are three main factors responsible for the drop:

  • The U.S. economy continued to underperform and looks like it may be headed into another recession. This has depressed bond yields.
  • The threat of a Greek default continues to hover over the markets and push investors into the relative safety of Treasury bonds, causing yields to drop.
  • The Fed has sold shorter maturity bonds and is buying longer maturity bonds in an effort to drive longer-term yields lower. It appears to be working.

Could 15 Year Rates Go Below 3%?

It's possible yields on 15 year fixed rate mortgages could go below 3%. Looking at the three factors above, the U.S. economy appears to be decelerating instead of getting better. That will drop yields. The Greek default crisis is not resolved and will most likely get worse before it gets better. It's also possible default fears will spread to other vunreable European nations - Italy and Spain - and cause a further flight to U.S. debt. If these two things happen, the Fed will continue to intervene in the markets.

Is is possible this worst case scenario will happen? Yes. Does that mean you should wait to buy a home or refinance? No. Rates continue to hit historic lows. Take the cheap money if you can get it and if it makes economic sense

Is a Reverse Mortgage Right for You?

What’s a ‘Reverse Mortgage’?

A reverse mortgage is a type of mortgage that allows a homeowner to borrow money against the value of their home. The borrower does not have to repay the mortgage’s principal or interest. The mortgage is repaid when the house is sold or the borrower dies.

After accounting for the mortgage amount, the rate of home appreciation, the loan’s length, and the accrued interest rate, the transaction is structured so that it ensures the amount of the loan will not exceed the home’s value over the loan’s life.

Looking for a regular mortgage? Get the best rates here.

The lender often requires that there are no liens against your home. All existing liens should be paid off with proceeds from the reverse mortgage.

A reverse mortgage provides people with the income they can tap into. The main advantage of a mortgage is that the borrower’s credit rating is not relevant, and in some cases, may not even be checked since the borrower does not need to make any payments.

With a reverse mortgage, the home serves as collateral. When the borrower dies, the home must be sold to repay the mortgage. In some cases, the borrower’s heirs will have the option of repaying the mortgage and retaining ownership of the home.

The origination costs on a reverse mortgage are much higher than other types of mortgages. These costs accrue interest and become part of the initial mortgage balance. If the borrower is a senior citizen with good credit they should carefully analyze their options to determine if a home equity loan or traditional mortgage is a better choice for their situation.

How Does a Reverse Mortgage Work?

A reverse mortgage is designed to help seniors become financially stable during retirement. This is a type of home equity loan, intended for people who have a fixed income. The money available to a borrower is determined by the borrower’s age, how much the borrower owes on their mortgage and other home loans, and the home’s values.

Older borrowers can draw more money through this loan program. The youngest spouse living in the home is the basis for calculating the loan amount.

A borrower can receive payments from this mortgage as a line of credit, a monthly payment, or a lump sum.

Borrowers won’t have to make payments as long as they – or their spouse – lives in the home. Yet, if both the borrower and their spouse pass away, or move out of the home, then payment is due.

If the borrower, or their heirs, sell the home, the proceeds go towards repaying the loan. If the home is worth less than the amount owed on the loan, all the sales proceeds will go towards repaying the loan and the mortgage will be considered paid.

There have been numerous news reports in the past few years of spouses being evicted after one of them, the one listed on the reverse mortgage, passes away. The new reverse mortgage rules, which took effect in 2014, offer better protection for the nonborrowing spouse, which allows them to stay in their home, after the borrower’s death.

Will I Still Own My Home?

Some people believe that if you have a reverse mortgage, the bank owns your home. That’s not true.

With a reverse mortgage, the bank has a lien on the house, the same as a tradition mortgage or any type of home loan. The mortgage has the first claim on any proceeds from a home sale. But, the home itself is still owned by the borrower.

There are some restrictions that apply to ownership of a home with a reverse mortgage.

This is a type of owner-occupied loan. The home must be occupied as a primary residence by the borrower or their spouse. The house cannot be leased to another resident.

Why Do People Take Out a Reverse Mortgage?

Many borrowers use their reverse mortgage to pay down their debts and cut their monthly paymnts. These debts include consumer debt, home equity loans, and the existing mortgage.s

Others may use this loan in the form of an open line of credit to help cover unexpected expenses.

By having funds in a line of credit, a senior can hold onto other assets like stocks and bonds. They can use the funds from a reverse mortgage to cover unexpected costs, instead of having to sell off their other assets.

The Popularity of Reverse Mortgages

In the 1990 fiscal year, the program’s first year, only 157 reverse mortgages were made, according to the NRMLA. The number of reverse mortgages taken out annual, spiked in the 2000s, peaking at 114,692 loans in the 2009 fiscal year.

During the Great Recession, the number dropped sharply, going down to 79,106 the next year. During the 2015 fiscal year, which dated from Oct. 1, 2014, through Sept. 30, 2015, people took out 53,372 new reverse mortgage loans. This was slightly higher than the 51,642 reverse mortgages taken out in 2014.

Since this program began, a total of 911,314 reverse mortgages has been taken out, according to the NRMLA. That number is expected to reach 1 million during the first half of 2016.

Take the Interest and Fees into Account

If you take out a tradition mortgage, the interest is included in your monthly payments. You pay a little bit of interest at a time. Since a borrower doesn’t make payments, during the life of the loan, the interest on a reverse mortgage builds up. The interest rate for a reverse mortgage is like other types of mortgages.

That means over the life of the loan, the amount of debt will increase. The interest can “eat up” any equity remaining in your home.

You also need to remember that although a reverse mortgage borrower doesn’t have a mortgage payment to make each month, the homeowner will still be responsible for paying taxes, homeowners association fees, homeowners insurance and other costs associated with homeownership. If a homeowner fails to make these payments, it may result in a default, which means the immediate repayment of the reverse mortgage.

Do Your Research

There are many resources available online to help people understand reverse mortgages.

The National Council on Aging and AARP have online resources to help explain reverse mortgages to potential borrowers.

The Federal Housing Authority, the Consumer Financial Protection Bureau, and other government agencies also offer information and online guides with information about reverse mortgages.

Talk to a Professional

Before getting a reverse mortgage, a potential borrower must attend a counseling session with a certified reverse mortgage counselor. This must be done before completing the application.

Lenders must provide a potential borrower with a list of several reverse mortgage counselors or agencies. It’s up to the client to choose a counselor and schedule a session. If the lender says you don’t have to attend a meeting or tries to steer you towards a specific counselor, that should be a red flag.

If you look on the HUD website, you’ll find a complete roster of certified HECM counselors.

Bring Your Family into the Conversation

Most lenders will say that the decision of whether or not, to take out a reverse mortgage should be made between the borrower and their reverse mortgage sales person. But, since this decision will affect the entire family, you may consider this to be a family decision.

A potential borrower should consider discussing their decision and how it may affect their heir’s inheritances and their estate. This should be done early in the reverse mortgage process.

Watch Out For – and Report – Scams

Reverse mortgage counselors and lenders try to watch out for clients who may be told to get a reverse mortgage as part of a scam. However, they are not able to catch all the fraudsters.

One scam involves people who offer seniors in a low-income community a “free” house. They move them into recently renovated fixer-uppers. Then they have them take out a reverse mortgage, and the scammer takes all the loan proceeds.

Other borrowers have been scammed when their house went into foreclosure. They were approached by an unscrupulous lawyer who promises to fix their problem for a fee. The lawyer disappears after the fee is paid.

If you suspect a scam, or if someone involved in your transaction is not following the law, tell your lender, loan office and reverse mortgage counselor. Also, file a complaint with your state Attorney General’s office, Federal Trade Commission, or the state’s banking regulatory agency.

Explore Other Options

Reverse mortgages are not perfect for everyone, so you should look for other options before you take this step.

First, look at refinancing the mortgage while interest rates are low in order to trim your payments.

If you have trouble making mortgage payments, you should research government programs in your area.

There are many different government programs that reduce your loan balance and make it affordable to stay in your home. These programs have various names depending on the state, like Florida’s Hardest-Hit Fund and Keep Your Home California. There are mortgage assistance programs available from some local governments.

And there’s a regular home equity loan which can help you get immediate cash, as long as you can handle another monthly payment.
High Credit Homebuyers Having Trouble Getting Jumbo Mortgages

In Massachusetts even borrowers with good credit are having trouble getting a jumbo mortgage. The credit crisis seems to have spread beyond just the sub prime market.

The Boston Globe ran a good article on the spreading impact of the tightening of mortgage credit. Residents in Massachusetts, even those with good credit, are having a much harder time getting jumbo loans or are getting loans are significantly higher rates. The rate on jumbo loans increased by 75 basis points (3/4 of a percent) in the last week. Jumbo loans are loans above the $417,000 purchasing limit of Fannie Mae and Freddie Mac. Lenders have become increasingly concerned about mortgages that they can't sell off to either of these agencies.

Another part of the article that I found interesting was where it discussed one homebuyer who was having trouble getting a home. It mentioned that he was surprised even though he only planned to put down 5% of the purchase price. Is it just me or does that seem like a paltry payment? Wouldn't he have to pay PMI? It seems to me that if you want to buy a home you should be willing to put down at least 10% if not 20% of its value.

Getting the Type of Mortgage that Is Best For You

Choosing a mortgage loan should seem like a straightforward process; you borrow money from a lender for a specified amount, for a set period of time, and pay it back. However, getting a loan you feel comfortable with, one that's flexible during good times and bad, can be a challenge.

Mortgage loans basically fall into one of two categories: government or conventional. Government loans are normally insured by the Federal Housing Administration (FHA) or the Veteran's Administration (VA). Some offer lower down payments and most offer favorable terms.

Conventional loans can be either conforming or non-conforming. Conforming loans follow the guidelines set forth by The Federal National Mortgage Administration (Fannie Mae) and The Federal Home Loan Mortgage Corporation (Freddie Mac). These types of loans can be either fixed or adjustable. Each is tied into a specific rate, term and limit which can vary from lender to lender. Non-conforming loans, on the other hand, do not adhere to any strict guidelines.

How do fixed-rate mortgages work?

Fixed-rate mortgages retain the same APR throughout the life of the loan. However, the property tax and homeowner's insurance, if built into the cost of the loan, may change over time. The most popular type of fixed loan is a 30-year term.

For those who prefer a shorter timeframe, a 15-year fixed mortgage may be a better option. While the amount of time it takes to repay is shorter, you can usually secure a better interest rate (.25-.50% lower than a 30-year fixed). Besides a 15- and 30-year term, fixed loans are also available 40- and 20-year terms.

Here are some other benefits and drawbacks that a conforming fixed loan has to offer.

Conforming Fixed Mortgage Loan Types

Types of Mortgages Advantages Disadvantages

15- or 20-Year Fixed

  • Interest rate and payment locked-in for the duration of the term should interest rates rise
  • Shorter amortization period allows for a quicker loan repayment leading to equity build-up
  • If interest rates go down you’re still locked-in to your original rate unless you refinance
  • Higher monthly payments than a longer term loan

30- and 40-Year Fixed

  • Interest rate and payment locked-in for the duration of the term should interest rates rise
  • Lower monthly payments due to a longer amortization period
  • If interest rates go down you’re still locked in to your original rate unless you refinance
  • Slow equity build-up since initial payments are mostly interest

How do adjustable rate mortgages work?

Unlike fixed-rate mortgages, Adjustable Rate Mortgages (ARMs) are based on shorter term securities that fluctuate upward or downward based on today's leading indexes (e.g., Constant Maturity Treasury (CMT), London Interbank Offering Rate (LIBOR), or Treasury Bill). A margin is added on top of the index rate by the lender to calculate the interest rate.

Because ARMs are adjustable, they go up and down at pre-set intervals during the duration of the loan. Some offer a low teaser rate to qualify potential buyers which accelerates to a higher rate thereafter. ARMs can adjust once a year, every month, or three to five years, and are typically amortized over a 30 year period. Some offer a lifetime cap which sets the maximum rate that can be charged during the life of the loan with some states having their own percentage limits.

Here are some of the benefits and drawbacks that an adjustable loan has to offer.

Conforming Adjustable Mortgage Loan Types

Types of Mortgages Advantages Disadvantages

Adjustable Rate Mortgage (ARM)

  • Lower payments can make it more attractive to qualify for a larger home
  • Some loans allow an option to convert to a fixed rate

  • Rates can adjust upward each year increasing your monthly payments
  • If even possible to convert to a fixed rate loan, the process may require payment of a conversion fee

Interest-only ARM

  • Affordable monthly payments during the initial interest-only period of the loan
  • Can refinance or pay off the loan after the interest only period
  • Can invest your principal savings into a higher yielding investment
  • Higher monthly principal and interest payments once the interest-only payment period ends
  • May not be disciplined in saving up for the pay-off amount
  • Initial interest payments go toward paying down a debt and not reducing the principal balance

Lower your payment with an Interest-only ARM loan

Another variation of the ARM is the Interest-only adjustable rate mortgage. This loan makes it affordable for borrowers to qualify for a loan by giving them the option to pay only the interest (not the principal) for the first 3-10 years of the loan. Monthly payments are usually more affordable. Afterwards, the interest rate adjusts to a traditional ARM at the current indexed interest rate with new principal and interest payments calculated for the remaining term of the loan.

Example

A 30-year ARM loan of $250,000 at 7.50% APR has interest-only payments for 5 years. The payment during this time would be $1,522 per month. After 5 years, the payment would increase to $1,816 per month.

A comparison of all the different loan types shows the potential cost savings you can achieve during the first five years of an interest-only loan versus other conventional loans.

Monthly Payment Comparison for Different Loan Types
Type of Mortgage
Loan Amount
APR*

Monthly Payment**
30/5 year Interest-only ARM
$250,000
7.31%
$1,522.00
30 year fixed
$250,000
6.17%
$1,720.35
15 year fixed
$250,000
6.05%
$2,429.02
1 year ARM
$250,000
7.67%
$1,987.85
3/1 ARM
$250,000
7.40%
$1,915.98
5/1 ARM
$250,000
7.21%
$1,894.23

* APR based on national average and may vary.

** Monthly payment includes principal and interest except Interest-only ARM which is interest-only for the first 5 years then jumps to $1,816.59 for the remaining 25 years (principal and interest included.)

Sub-prime loans

Borrowers who have a low FICO score will usually fall into the less than perfect mortgage category. As a result, they'll qualify for a loan but at a much higher rate. Lenders may apply stiffer pre-payment penalty fees in the form of interest payments to dissuade borrowers from building up any equity in their home. Some lenders may require a " balloon" payment to pay off the remaining balance of the loan after a fixed period of time.

Compare the best mortgage rates.

Mortgage Prequalification versus Mortgage Preapproval

What's the difference between mortgage prequalification and mortgage preapproval? Which one is better?

Pre-qualification is preferable to pre-approved. Pre-qualification means that a lender has assessed and verified your income, assets, current debts, and credit score, and determined your ability to close the loan, your ability to re-pay the loan, and the size of loan they will lend to you. A pre-approval is a less rigorous review of your financial state than a pre-qualification; while a lender will assess your income and credit score, limited verification steps are normally taken.

In either case, your lender will provide you with a letter that you may share with your offer contract. Typically a pre-qualification letter can be completed in a matter of hours, although some lenders may take longer.

How Does Getting Pre-Qualified Benefit You?

· You will be able to shop with the confidence of knowing your exact price range.

· You can identify credit problems that can be addressed early in the lending process.

· You will typically have more negotiating power, as some sellers see more strength in offers from pre-qualified buyers.

· If you are self-employed or a commission-based buyer, pre-qualification can demonstrate financial backing if your income fluctuates more than those of salaried buyers.

· Pre-qualification gives first-time homebuyers the advantage of equalizing their offer with similar offers made by previous homeowners.

Other Pre-Qualification Facts?

· Pre-qualification is offered by most lenders, including at no cost.

· The pre-qualification process is not comprehensive and therefore is not guaranteed, nor is it considered any type of loan commitment. It simply shows that you’ve approached a lender who was serious about helping you determine what you can afford and will walk you through the process.

Why you should maintain a good FICO score

Derived from your credit history report, credit scores are based on points you receive for being a good borrower. The most common scoring system used for mortgage approvals is done by the Fair Issac Corporation (FICO), which accesses the three main credit reporting bureaus (Equifax, TransUnion, and Experian.)

Credit scores can range from a low of 300 points to a high of 850. People with average credit usually score around 620, good credit at 660, and excellent credit above 740. People with higher credit scores more easily obtain mortgage loans and also are able to secure lower interest rates vs. those with lower scores.

Example

Let’s imagine a 30 year fixed mortgage of $300,000. Someone with a credit score of 740 or higher could get a loan at a 4.125% interest rate, and a monthly payment of $1454. Another person with a credit score of 660, however, would get a loan with a higher interest rate of 4.625% and a monthly payment of $1542, a monthly difference of $88 (or annual difference of $1056). Over the life of the loan, this person would pay $31,849 more in interest as compared to the person with a 740 credit score. Another person with a credit score of 620 or below would have an even higher rate and payment, if they were even able to get a mortgage loan.

How to get the best rate

A good strategy for securing the best rate would be to clean-up your credit report at least six months prior to applying for a mortgage loan. Anyone may obtain their credit report for free once a year from www.annualcreditreport.com. Maintaining a debt-to-income ratio of less than 36% could boost your score by as much as 10%. Lenders like to see a history of long-term credit and ability to pay off a loan over time. The goal of any loan applicant should be to make sure their credit report is as accurate and sound as possible.

After you are under contract on a new home, your lender will complete the full loan approval process, lock-in your interest rate for a specified period of time (usually 30 to 60 days), and provide you with an estimate of your closing costs and monthly payments.

Find the best mortgage rates.

Which Mortgage is Right for Me?

Comparing 15-Year & 30-Year Fixed Rate Home Loans To A 10/1 ARM

When a homeowner goes to a lender and they starts the process for filling out a mortgage loan application, it is important to know exactly what kinds of mortgages are available, along with the advantages and disadvantages of each. Here we takes a look at fixed rate 15 and 30 year mortgages versus 10/1 adjustable rate mortgages (ARMs).

Fixed Rate Mortgages

A fixed rate mortgage is onewhere the interest rate will stay the same all throughout the full life of the loan. These loans are by far the most popular, representing more than 75% of home loans. They will usually come in terms of 10, 15 or 30 years, with the 30 years being the more popular option. While the 30 years remains most popular, the 15-year will build equity a whole lot faster.

The big advantage that comes with a fixed rate is that a homeowner knows exactly what the principal as well as the interest payments will be over the entire duration of loan. This will allow the homeowner to budget a lot easier because they understand the interest rate will not change over the duration of the loan.

Fixed rate mortgages are not just the most popular for home loans, but they are known for being the most predictable. The rate gets agreed upon in the beginning and the rate stays the same and charged over the duration of the note. Homeowners can budget easily for the monthly payments each month for the loan. When rates are high and the homeowner gets a fixed rate mortgage, the homeowner is able to refinance later on when the rates go down. If interest rates go down and you want to refinance, the closing costs will have to be paid to do so. Some banks that want to keep good customer accounts may write off these closing costs or otherwise enable to customer to refinance without incurring fees. On the other hand, buyers who purchase when rates are low keep the rate locked even if the broader interest rate climate rises. However, home buyers do pay a premium for locking in the certainty, as the interest rates of such fixed rate loans will usually be a bit higher than an adjustable rate home loan.

A home purchaser who is not planning to be in their home for a full 30 years, one who believes that they will refinance or pay off their mortgage sooner, or one who can easily handle the monthly payments should seriously consider shorter term fixed-rate mortgages.

See the best 30 year fixed-rate mortgage rates today.

10/1 ARM

An adjustable rate is mortgage loan where the interest rate will change based upon a certain schedule after there is a fixed period at the beginning of the loan. This is called an ARM, or an adjustable rate mortgage. Getting an ARM could allow you to qualify for loan amounts that will be higher, therefore you can get a more valuable home. However, this kind of loan is considered to be riskier because payments can change significantly if rates rise. In exchange for any risks that are associated with ARMs, the homeowner ordinarily will be rewarded with interest rates that are lower than a 30-year fixed rate or even a 15-year fixed rate. When a homeowner gets an ARM, they are usually getting a 30-year loan where the rate will change each year on the anniversary after a certain point.

The 10/1 ARM in particular comes with an initial interest rate that is fixed for the initial 10 years of the loan. After this 10-year period is up, the rate adjusts every year for the loan remainder. The loan will have a 30 year life, so that homeowner will have initial stability for a 30 year mortgage at a lower cost than that of a fixed rate mortgage that may have the same term. However, the adjustable rate mortgage might not be the best choice for anyone who is planning on owning the same home for more than 10 years unless they are able to make extra payments and plan on working to pay their loan early.