New York

Image Courtesy: pixabay.com

Three Tips for the Lowest Refinancing Rates

Is now the best time for you to refinance your mortgage? If so, consider these suggestions before making your final decision.

If you are like many other American homeowners these days, you may be looking to take advantage of the low mortgage rates these days. If you already own your home, refinancing may be an option for you so you can save thousands of dollars over the term of your mortgage loan. But before you do that, here are three things you should consider before calling a mortgage refinancing agent.

Refinance the Entire Loan

Many people refinance their mortgage, but they only refinance a portion of their mortgage. If you are going to refinance your home, include the entire amount of the loan in the refinance. By doing the entire mortgage, you have a better chance of getting the lower rates on your loan. Refinancing only part of your mortgage makes you’re a bigger risk for lenders which will result in less favorable loan terms for you.

Don’t Use All Your Equity

When refinancing, you might think it is a good idea to include all of your home’s equity in the refinance. This may be good in some situations, but it is generally not recommended. Instead, you should choose a home equity financing loan or consider applying for a home equity line of credit soon after getting the refinance loan. This gives you the opportunity to refinance your mortgage with lower rates and use the equity for something else that you may need instant cash for.

Consider Buying Points

Many homeowners do not realize that they can buy points. This means that you can put up some money upfront in order to get a lower interest rate for the term of your loan. This is typically only beneficial if you plan on staying in your home seven years or more or else you won’t recoup the cost of buying the points. To see if buying points makes sense for your particular financial situation, consult with a mortgage broker or trusted financial advisor to crunch the numbers for you before you make that decision.

Before making your final decision to refinance, always do the math and determine what the best decision is for the long run. Refinancing might seem like a good idea for the immediate future, but it may not make financing sense for the long term of the loan.

Mortgage Closing Costs

Once you've been approved for a mortgage, found a house, made an offer, and the offer has been accepted, you are close to calling your property home. What's left is to finalize the documents which will transfer ownership of the house from the seller to the buyer. The "close" or "settlement" usually involves the seller, real estate agent, lawyer, escrow agent, mortgage lender and buyer, and title company.

Once you've been approved for a mortgage, found a house, made an offer, and the offer has been accepted, you are close to calling your property home. What's left is to finalize the documents which will transfer ownership of the house from the seller to the buyer. The "close" or "settlement" usually involves the seller, real estate agent, lawyer, escrow agent, mortgage lender and buyer, and title company.

How the process works

The escrow agent and title company will present you with a variety of documents to examine and sign; title, insurance, escrow, and others - each with their own fees. Expect to pay 3-5% of your mortgage amount toward closing costs. Most fees are negotiable, with lenders picking up some of the costs upfront, while others require some costs to be paid by the borrower upfront, or built into the cost of the loan.

Settlement Costs Estimates

FEE - Average Cost(s)

Administration - $250.00

Application - $250.00

Appraisal - $300.00

Attorney fees - $300.00

Credit report - $25.00

Document preparation - $150.00

Escrow - $735.00

Fire insurance - $300.00

Flood certificate - $20.00

Hazard insurance - $300.00

Origination fee (points) - $2,500.00

Pest Inspection - $150.00

Private Mortgage Insurance (PMI)** - $2,500.00

Processing - $4,500.00

Recording fee - $475.00

Tax services - $60.00

Title examination - $150.00

Title insurance - $300.00

Underwriting - $300.00

TOTAL = $9,165,000 (3.66% of $250,000)

* Based on a $250,000 mortgage. Costs may vary by lender.

** If down payment is less that 20% of the loan amount.

For a description of the terms above, please see our mortgage glossary.

What is Private Mortgage Insurance?

Your lender may advise you to set up an escrow account should your down payment be less than 20% or if you're a high credit risk. Less money down means the greater the risk the lender needs to assume. So to guarantee your property tax payments and private mortgage insurance (PMI) premiums, a small percent of your mortgage will be set aside each month to cover your payments. Your PMI rate will vary based on the mortgage amount and covers the lender in the event you default on your payment.

Should you pay extra for points?

Should you secure a lower interest rate on your mortgage you can expect to pay a certain percentage to the lender in the form of points. Points or origination fees are what lenders charge in interest to reduce the rate of the loan. It can be paid upfront or built into the cost of the mortgage. One point is equal to 1% of the mortgage amount (e.g., one point on a $250,000 loan equates to $2,500) which goes to the lender at closing.

Read an article on whether or not it makes sense to pay mortgage points.

What are Your Options Besides Refinancing?

Is your mortgage payment becoming more and more difficult to pay each month? Is refinancing your home to get a lower payment simply out of the question? If so, there are other options available to you.

Are you having problems making your mortgage payments but refinancing your mortgage loan just isn’t an option for you? If so, there are other options available if you are willing to do some legwork in order to make it easier to pay your monthly house payment. Here are three such options.

1. Ask your lender if you can recast the amortization of your mortgage. For homeowners who have had their mortgage for at least five years and your loan payments have been on time every month, you may qualify to have your mortgage recast. A recast means that your mortgage loan is recalculated so that you can spread out the amortizing payments over the period of the loan. This can be especially effective if have paid down the mortgage principal at some point. It is also possible to recast a mortgage so that the principal amortizes at a slower rate at the beginning of the loan (lowering payments in the near years since they are primarily interest payments). In many cases, therefore, a recast will lower your monthly mortgage payment quite a bit to make it easier on your budget. However, since a recast delays paying off principal, it extends the loan and means that you will be paying more in the long run over the term of your loan.

2. Ask for a lower interest rate. Mortgage lenders are often willing to work with you when you run into trouble making your payments. One thing that your lender may be willing to do is to lower your mortgage rates. If you have a good record of making your payments on time, you will be more likely to qualify for an interest rate reduction so be sure to send those payments when they are due. Before you ask for a lower rate, you should be sure to check the current interest rates in your area.

3. Ask about modifying your mortgage loan to an interest-only mortgage for a couple years. By turning your current traditional mortgage into an interest-only mortgage, you can lower your monthly payment significantly. However, this may be the most difficult option as many banks are not as willing to do this as they are the other options.

These are just a few options available to today’s troubled homeowners. But just because they are options does not mean that your mortgage lender will be willing to do it. If you have a history of late payments or other problems with your mortgage payments, your bank will be less willing to work with you. That’s why it is so important to contact your lender as soon as you start having financial problems. Never ignore the problem. The sooner you call your lender about your financial problems, the more options you have when it comes to working out an agreement.

See mortgage refinance rates where you live here.

Six Hidden Costs of Refinancing Your Mortgage

Refinancing your mortgage is a great way to save money on the life of your loan. But you should know the extra fees associated with refinancing to see if this is the most cost efficient option for you.

With mortgage rates at rock bottom lows and staying at near these record lows for several weeks, the option of refinancing your current mortgage may seem like an enticing deal. And for many homeowners, it can save you thousands of dollars over the life of your loan. But that’s only if you are careful during the process of refinancing your mortgage. There are many hidden costs that are often bundled into a refinance and some of these costs are avoidable if you know what to look for. Here are six of the most common hidden costs that you should know about when you refinance your mortgage.

Loan Origination Fees

The loan origination fee is a common cost of refinancing your home. This fee is charged for evaluating and preparing your loan documents. You typically can’t avoid this fee, but you can shop around to different mortgage lenders and find the one that charges the least for the origination fees. These fees can generally be as much as 1.5 percent of the principal, but you should be able to find lenders that charge much less than that.

Application Fee

When you apply for a refinance on your mortgage, you are going to pay an application fee. This is a fee that you pay upfront and the lender will keep this fee even if you get denied for a mortgage refinance. An application fee generally costs between $75 and $300 depending on the particular lender and other factors, but you can usually negotiate this cost to drop it down or even have it waived in some cases.

Appraisal Fees

The appraisal fee is not always necessary when refinancing your home. If you have had an appraisal in the last few years, your refinancing lender may waive this fee which can cost you and extra $300 to $700 depending on the size of your home, the area where you live and the mortgage refinancing company that is handling your loan.

Inspection Fees

Depending on the length of time you’ve owner your home, your refinancing lender may require an inspection of your home. The home inspector will check for termites, structural damage, pests and other things that could impact the overall value of your home. Inspection fees can cost up to $350 but if you have only had your home for a couple years, you may not need to pay this fee.

Attorney Fees

When you refinance your home, you generally have to pay fees for attorneys to conduct the closing of the deal. Lender fees can cost between $500 and $1,000 depending on how much has to be done for your particular refinancing transaction, the principal balance and other factors.

Prepayment Charges

As with many mortgages, you may be charged a fee if you pay off your loan early. This is also true with refinancing your mortgage. When you refinance, be sure to read the fine print on the refinancing contract. You could be charged extra fees which could be as much as six months’ worth of interest payments if you decide to pay off your mortgage sooner than the contract has scheduled.

Refinancing your mortgage can save you thousands of dollars over the long run. But if you don’t consider these costs and add them into your expected charges, you may not be saving any money at all. Do your research and add up the costs before making your final decision to refinance.

Compare refinance rates where you live here.

Mortgage Advice for Lawyers, Doctors, and Young Professionals with High Student Debt

In today's mortgage world, doctors, lawyers, and other professionals can find that getting a mortgage after graduation can be very difficult if they have high student debt and lack significant job history. We ask the experts for some tips on what these graduates can do to improve their chances of being approved for a mortgage.

Many doctors, lawyers, and other graduate degreed professionals finish school in their late twenties to early thirties with a good, steady paycheck and a desire to upgrade their living conditions after many years on a student budget. Part of the plan often includes purchasing a home. Most young professionals assume that with their high salaries and great future job prospects, they should have no trouble receiving a mortgage. In today's mortgage world though, doctors, lawyers, and other professionals can find that buying a home after graduation can be very difficult if they have high student debt and lack significant job history.

While doctors, lawyers, and other professionals often graduate into jobs with high salaries, have great credit histories, and may even have money for a down payment, high student debt is often a huge obstacle to securing a mortgage. When determining whether to give a loan, a key metric used by lenders is the debt to income ratio, calculating by taking all of a borrowers monthly debt payments (student loan, credit card, auto loan, etc.) and dividing it by their gross income. Thus, a doctor with $3,000 in debt payments and with a gross salary of $10,000 would have a debt to income ratio of 30%. In general, borrowers with ratios over 45% will not quality for a mortgage. Gloria Shulman, the founder of Centek Capital Group in Beverly Hills stated that "even if deferred, student loan debt is a huge issue for young borrowers... medical or other graduate school debt can be a killer if you don't go into buying property with a debt management plan." Doctors and lawyers because of the number of years of graduate school required, often have the highest amount of debt.

The second reason young doctors and lawyers may find it difficult to get a mortgage is that many mortgage lenders require two years of stable work history before providing a mortgage. A new graduate doesn't have the work history required by many lenders.

But difficult doesn't mean impossible. Here are some tips provided by lending experts from around the country:

Get a Co-Signer

Ms. Shulman recently helped a young neurosurgeon find a loan product after multiple bank denials by working a deal where his parents were co-signers in name only. Having parents server as co-signers places risk on your parents and is often not advised by financial planners, but if you have a great relationship with your parents, and are confident in your future earnings, if might be a sensible step to consider.

Buy a Starter Home

Don't have your sight set on the McMansion down the street, start with more modest aspirations. Look to buy a home with a mortgage of less than $417,000 (a conforming mortgage). Roy Sperr from Equity Source Mortgage in Minneapolis provided the following guideline:

If you have your first pay stub as a new professional employee, are borrowing less than $417K and have a Debt ratio of less than 45% (divide your total monthly base income into your monthly debts to calculate) If you are .45 or less you can most likely buy a home.

If you are buying a home that will result in a Mortgage Loan higher than $417K you are considered a “Jumbo” borrower. This loan is not sold on the secondary market (Fannie and Freddie) and is subject to higher scrutiny.

Look for HUD/FHA Loans

Jason Bonarrigo from Residential Mortgage Services in Braintree, MA says that "with a HUD/FHA loan, "if the lender can document student loans are deferred for more then 12 months, then the person does not have to use the student loan debt in the qualifying ratio's." HUD/FHA loans are popular government sponsored loans that often require lower down payments when purchasing a home. In general, HUD/FHA loans are only for conforming mortgages (less than $417,000) and often have expensive fees, but they are worth investigating.

Consolidate and Pay Down Debt Where Possible

The cleaner you can make your debt situation, the better. Mr. Sperr also offered the following advice:

Before applying make sure you do everything you can as a borrower to understand your student loan debt and its repayment terms. Make sure you know your other outstanding debts.

a.) Consolidate all separate student loans if possible into one payment.

b.) Pay down credit cards, car loans and other smaller debt that can be
controlled to improve ratios.

Malcolm Hollensteiner, Director of Lending Sales and Products at TD Bank advised borrowers to see if a family member can provide a gift and use it to "to eliminate consumer debt, rather than putting family money directly towards a house. In certain cases, eliminating or reducing consumer debt helps to increase buying power more than a higher down payment would."

Buy With a Friend or a Significant Other

Mr. Hollensteiner also advised that pairing up with a friend can increase a buyer's chances of obtaining a mortgage, "assuming both do not have considerable college debt." He advised that individuals considering this route "be cautious and thoroughly think the decision through. Future plans – including marriage and job relocations - could make this kind of partnership inconvenient down the road."

Another option is to purchase a house with a significant other, especially if the relationship is headed towards marriage. Once again, the borrower should carefully weight the pros and cons and think through what happens if the relationship does not work out.

Explore mortgage rates here.
Housing Construction Back to 1991 Levels

Housing construction continues to drop as an oversupply of houses keeps the builders on the sidelines.

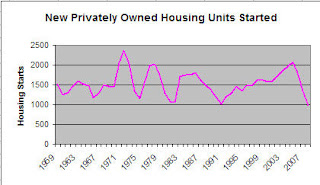
PrivatehousingstartsHousing construction has dropped over the last two years as real estate sales have slowed. This makes sense since there is an oversupply of houses. The Department of Commerce reported yesterday that privately-owned housing units authorized by building permits in June were at a seasonally adjusted annual rate of 1,091,000. This is 11.6 percent (±1.2%) above the revised May rate of 978,000, but is 23.9 percent (±1.3%) below the revised June 2007
estimate of 1,433,000.

Housing construction is a major part of the economy and a slowdown in this sector is thought to have reduced GDP between one-half to one percent.

It's also hurt some of the popular housing stocks. Toll Brothers, one of the nation's biggest builders, is down from its high of 55 in July 2005 and now trades at 19. Home Depot has also taken a tumble and is trading at half of its 52-week high.

HomeDepotStock

Housing Starts in May Fall 32% from Last Year According to Census Bureau

Housing permits and starts are all down significantly from last year.

Housing Starts The US Census Bureau released their housing data for May and it showed continued deceleration in residential home construction:

"Privately-owned housing units authorized by building permits in May were at a seasonally adjusted annual rate of 969,000. This is 1.3 percent (±1.2%) below the revised April rate of 982,000 and is 36.3 percent (±1.3%) below the revised May 2007 estimate
of 1,522,000.

Privately-owned housing starts in May were at a seasonally adjusted annual rate of 975,000. This is 3.3 percent (±10.7%)* below the revised April estimate of 1,008,000 and is 32.1 percent (±5.1%) below the revised May 2007 rate of 1,436,000."

As the chart on the right shows, housing starts have fallen significantly from their recent peak in 2005. Nonetheless, the drop-off is consistent with other housing slowdowns and doesn't appear catastrophic - yet. I calculated the 2008 data by avering the first 5 months of the year and then multiplying by 12. A further slowdown in future months could bring the level to an historic low.