
American Flag

Best Online Savings & Money Market Account Rates 2026

Best Online Savings & Money Market Account Rates

Recent Articles


The Federal Reserve End March 2024 Meeting Again Holds Interest Rates at 5.25-5.50% Target

The Federal Reserve ended its March meeting leaving interest rates at their current target. The members unanimously indicated that they anticipate three quarter-point rate cuts before the end of 2024. Given that January and February inflation data was bumpy, Chairman Jerome Powell was non-committal on a timeline for the first cut. He said that the Fed will remain data-dependent and will not make any rate changes before its May or its June meeting. He also indicated that if inflation were to pick up dramatically, the Fed could still raise rates, although he tempered that statement by saying that he sees no indication at the moment that such action will be necessary.

What is clear is that the Fed is completely beholden to its dual mandate (price stability and maximum employment) and wants to see clear indications that inflation is heading decisively towards its 2% target before it begins to reign in interest rates.

I personally am in the camp that would be betting that the Fed will not move in May. There remains a possibility that developments in the Middle East and/or Russia could cause a global spike in energy costs again and that would factor right through to inflation. Even if the focus is not on the risk of an oil price spike, the Fed needs to get 3 months or so past the recent inflation data until it begins to cut.  And, that would put the first rate cut in the June meeting in the best-case scenario.

Interestingly, Chair Powell was asked about criticism that he has received from Republican lawmakers that high interest rates are burdening the American consumer, and about a letter that he has received from Senators Whitehouse and Warren that high rates are grinding renewable energy investment to a halt. His response was that he is sympathetic to those concerns, but that the Fed is charged by the Senate to pursue its dual mandate.

Those of us who invest in the renewable energy sector are very troubled by the slow pace of investment and it is clear that large project finance transactions cannot achieve the necessary internal rates of return (IRRs) when discounted by current rates. Unfortunately, Powell's answer to this question was correct and the Fed cannot be guided by the climate crisis while at the same time focusing on its dual mandate.

Does An Inverted Yield Curve Signal Recession – This Time Could Be Different

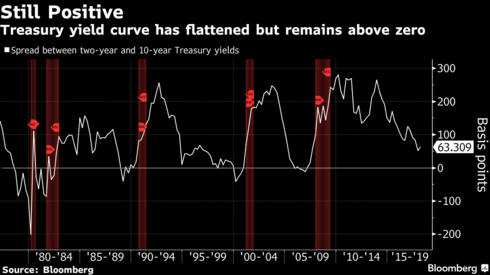
When I was in business school, I was taught that an inverted yield curve is an extraordinary precursor of a recession. Indeed, the empirical evidence is there. Of the five recessions since 1980, all have been preceded, by 6 to 18 months, by an inversion of the 2 and 10-year Treasury rates.

Treasury Chart


The yield curve now is getting close to flat (it is not inverted), and that is causing a lot of economists to appear on Bloomberg and CNBC fretting about a potential recession as early as late 2018.


What causes the correlation? Could this time be different?

I think, this time, that the inverted yield curve could be sending a different signal.

First, I am looking at the cause of the flattening yield curve. In particular, this time the compression of the yield curve is clearly caused by a true global debt environment. For the last decade, as the US has been recovering, 10-year and longer US Treasury bonds have been purchased by the Chinese and other purchasers. While this has enabled the US to fund its extraordinary debt and deficit in a way that might not otherwise have been possible, it has also prevented US government debt rates from expanding to offer a rate of return on long term debt that might be reasonably expected. Extraordinarily low inflation in the US has also been a factor.

Even as short-term rates have come up, there has been steady demand preventing long-term rates from going up as well. When the US 10-year moved above 3%, a couple of weeks ago, the dollar strengthened dramatically against every major currency as foreign accounts moved into dollars to chase yield. In fact, low long-term debt yields globally may continue to compress US debt rates, even as inflation creeps up

Second, I am looking at why a yield curve has led to past recessions. The fact that banks borrow at short-term rates and lend at long term rates and that banks have been pressured when the yield curve compresses or inverts has been a factor in each recession (and was the major cause of the 2008-2009 crisis).

But, in the post-crisis world, the major money center banks are operating in a way that involves much less interest rate risk. The major money center banks are lending short term with instruments like credit card loans at much higher rates than ever before. They have issued home equity loans that are more tied to short-term rates (see rates here). And, many of them are still making fortunes by paying 0.01% to 0.03% on deposits (you can get a better rate on short-term savings and money market accounts here). To boot, they have issued billions of dollars in structured notes that provide a hedge from interest rate risk and enable them to pay nothing for their capital for the full duration of an inversion.

So, I would submit that this time could be different, and while interest rate movements affect your own finances, the compression and possible inversion may say very little about the US economy.


The Wisdom of Old or Not-So-Old Age

While Bankrate no longer provides the most accurate and comprehensive information on bank rates (that distinction now belongs to BestCashCow or RatesAndInfo.com), they do sometimes produce interesting surveys.

Their latest survey indicated that 5% of those aged 18 to 37 say bitcoin is the best place to put money they won’t need for 10 years or more, whereas only 1.2% of those aged 38 to 53 favor it for long term savings, and less than 1% of those aged 54 to 72 do.

I myself am not so old, though I do fall into the bracket of people aged 38 to 53. I cannot imagine what planet the 1.2% of my age cohort would trust bitcoin or any cryptocurrency, and I am startled that so many people who are younger would entrust their savings to these instruments.

While Bitcoin has fallen this year, it hasn’t collapsed completely as many - including myself – had predicted. It, however, remains an artificial asset, a mirage, and one where $7,000 per coin has no more fundamental value than $0.32.

With age comes the reality that a crisis in confidence in an instrument can cause pandemonium, confusion and widespread selling of assets representing a claim on fairly predictable future cash flows. History books will tell you that this has happened in 1929 and 1987. Even in the youngest age bracket, many can remember the internet crash of 2000-01 and the financial crisis of 2008-09. While fundamental strong assets were often devastated, fake assets (those assets not fundamentally backed by future cash flows) disappeared (eg., Enron collapsed in the aftermath of the internet crash).

To believe that bitcoin represents a store of value is to ignore those lessons and to bet on a constant and indefinite faith in a mirage that ignores fundamentals. It also assumes that there will be no hiccups in broader financial markets that would cause people to lift the sheets and look underneath.

Investors should stick with savings and money market accounts, CDs, bonds and equities as major components of their financial portfolios. Not bitcoin.