
American Flag

Best Online Savings & Money Market Account Rates 2026

Best Online Savings & Money Market Account Rates

Recent Articles


How Bank Failures in 2008 Compare to Tough Times in 1980's

We've now had five bank failures in 2008 and I wanted to see how we are doing compared to the real estate downturn in the 1980s and savings and loan crisis it precipitated. The results are interesting.

I read an interesting post in the Blog Calculated Risk today. The article showed that the five banks that have failed in 2008 so far (including Indymac) were a blip compared to the 574 that failed at the height of the Savings and Loan crisis in 1989. At that time, the government was forced to bail out the banking industry to the tune of tens of billions of dollars.

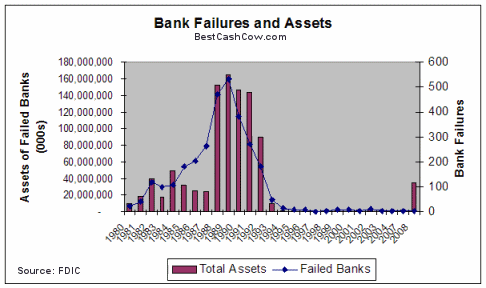
Some of the comments on Calculated Risk pose an interesting question. Maybe there were more smaller banks in 1989 so that while there might have been more bank failures, they were relatively tiny from an asset perspective. And maybe one bank failure today is larger than hundreds of smaller bank failures back then. Determined to see if that was the case, I went to the FDIC website, downloaded the data on bank failures and their respective asset sizes, loaded it into Access, did a query or two, and..presto:
alt

The bars show the combined assets of the failed banks for each year while the line shows the number of failed banks. As you can see, the number of failed banks is tiny today compred to ten years ago and so were their respective assets - until Indymac. $32 billion of this year's $34 billion in failed assets were attributable to Indymac.

Let's look at this another way. The chart below shows the average assets for bank failures by year.

alt

The largest bank failure was in 1984 when Continental Illinois National Bank and Trust Company, a $40 billion dollar bank collapsed. As the chart shows, other bank failures during that time kept the average relatively flat. Another intersting, fact, the failure of Continential Illinois was considered to be a forerunner of the S&L mess.

To all of this, add the fact that there are 50% fewer banks today than there were 10 years ago.

So, here's the real question. Is the average so high because small banks have done a better job managing their balance sheets and asset risks and remained solvent? Or is Indymac just an aberration and no more bank failures will be coming? Or, is Indymac, like Continental Illinois, a leading indicator of what will be fewer but much larger future bank failures?


Citibank offers up to $400 cash reward for L.A. residents who open new checking account

Earn up to $400 in Citibank's LA account deal, or $50 to $100 for opening a checking account anywhere in the country.

If you live in the Los Angeles area, you could make as much as $400 for opening a checking account with Citibank.

To start off, anyone who opens a regular checking account with Citibank is automatically eligible for a $200 bonus. Those who open a checking account with the Citibank Account Package (as opposed to the Citibank Checking Package) can earn the full $400. This is a limited time offer that expires August 22.

There are, however, a few limitations to this otherwise fantastic deal. Within the first 60 days after opening the account, you must deposit a minimum of $1,000. Upon initiating the account, you must also make at least one monthly direct deposit for two months.

If you're not a frequent spender, though, you may find yourself losing the $200 to $400 you gained due to another one of the account's restrictions. For the first two months, you must make five or more monthly debit card purchases or pay two monthly electronic bills. Compared to other checking accounts that don't incur monthly fees (although the majority are going to, eventually), this may not be a good deal after all because you'll end up depleting some of the bonus you received.

But, if you regularly have at least five debit transactions a month and have $1,000 free to deposit, the extra money could come in handy. Preferred customers (who have Citibank checking, mortgage, and credit card balances) may also be able to waive monthly fees.

Another advantage to this offer is the Citibank ThankYou Rewards program, which enables customers to claim rewards simply for regular banking activities that they already do anyway. To speak with a Citibank representative about this offer, call (626) 912-1625.

For those who don't live in the L.A. area, Citibank is still offering cash rewards for opening an interest checking account with either the Citigold ($100) or Citibank ($50) account relationship package. This deal also requires customers to deposit and maintain a balance of $1,000 for at least thirty days, beginning within the first month of the account.

For Citibank's special offers page, click here. For other great bank deals, click here.


You Are About to Get Killed in Bonds

Rate information contained on this page may have changed. Please find latest savings rates.

Many investors, commentators and financial managers have perpetuated and subscribed to the fiction that those who want to protect themselves from an overvalued stock market should be moving to bonds. In fact, a recent New York Times piece, described here, even mistakenly assumed described investors’ choices as being binary – stocks versus bonds.

The idea that bonds are somehow a safe investment comes from the fact that long-term bonds have appreciated dramatically over the last several years as interest rates have come down and expectations of their rising have diminished.

With the 10-year Treasury yielding 2.10% and with the Federal Reserve guiding towards a Fed Funds rate of 3% in 2019, I would argue that the only way long-term interest rates do not rise, and rise dramatically, is if we fall into an economic depression and the yield curve becomes inverted. Also, oil and commodity prices are currently tremendously suppressed because the monarchy’s policy of opening up reserves is causing too much supply to reach markets. An impeachment trial will change this, causing commodity prices and inflationary pressure to rise, and driving 10-year Treasury rates to levels that those in their 20s and 30s have never seen.

The impact of a turn in interest rates on bond prices will be dramatic. You can ask anyone who tried to sell a long-term bond in 1970’s how many pennies on the dollar they received for it. Alternatively, you can speak to anyone who bought a long-term bond in July 2012 when the 10-year Treasury was at 1.52% how much their brokerage account valued it in August 2013 when the 10-year Treasury was at 2.90%. Bond investors can quickly lose 30% to 50% of their principal should they need liquidity during a period of rising interest rates.

My view that another dramatic move up in 10-year Treasury yields – and dramatic fall in bond prices – is likely upon us is not unique. It is shared by Leon Cooperman and Alan Greenspan.

Your safety is found in savings accounts and short-term CDs.