American Flag

Best Online Savings & Money Market Account Rates 2026

Best Online Savings & Money Market Account Rates

Recent Articles


CD and Savings Rates Flat, Mortgage Rates Dow - Weekly Rate Update

Rate information contained on this page may have changed. Please find latest savings rates.

CD and savings rates showed virtually no movement over the past week. Mortgage rates have decended over the past three weeks, touching lows not seen since last April when the Fed began buying up mortgage backed debt.

This week the discussion continued about whether the Fed's 0% rate policy is leading to the creation of asset bubbles. Chinese and Japense central bankers went on record as stating that the Fed's policy has already led to asset bubbles in Asia that could create global imbalances. In particular, they were referring to the carry trade, in which investors borrow money in a country with low interest rates and invest it in a country with strong asset price growth or higher rates of return. "Liu Mingkang, China’s chief banking regulator, said that the combination of a weak dollar and low interest rates had encouraged a “huge carry trade” that was having a “massive impact on global asset prices”….

Bill Gross from Pimco probably got it right when he said:

"The Fed is trying to reflate the U.S. economy. The process of reflation involves lowering short-term rates to such a painful level that investors are forced or enticed to term out their short-term cash into higher-risk bonds or stocks . Once your cash has recapitalized and revitalized corporate America and homeowners, well, then the Fed will start to be concerned about inflation – not until. To date that transition is incomplete, mainly because mortgage refinancing and the purchase of new homes is being thwarted by significant changes in down payment requirements. The Treasury as well, has a significant average life extension of its own debt to foist on investors before the Fed can raise short-term Fed Funds."

The only good news for savers is that inflation for goods and services remains relatively subdued. The CPI rose by .3% in October. The index has decreased by .2% over the past 12 months. Leading the increase in October was energy and automobiles. While energy prices will probably continue to rise, look for auto prices to fall back now that cash-for-clunkers is over and the government is no longer subsidizing car purchases. Overall though, there is nothing on the goods and services inflation front that would push the Fed to raise rates.

The only inflation seems to be in assets and Bernanke doesn't believe this presents a problem at the moment.

CD and Savings Rates

CD and savings rates showed virtually no movement over the past week. The average savings rate according to the BestCashCow rate tables dropped one basis point to a new low of 1.62% APY. That's down from 1.70% APY a month ago. CD rates have mostly stabilized. The average one year CD rate is now 2.08% APY. That's up slightly from the last week and virtually the same average rate that we saw in October. For the fourth week-in-a-row 5 year CD rates held at 3.35% APY.

Looking at the yield ratio we have developed for deposit accounts, we see that the spread between savings rates and 36-month CDs is still close to its 12 month high. While it came down slightly, the trend is still up. This reflects the rate stability in longer term CD rates even as savings rates continue their glacial descent. The story is really the weakness in savings rates and the continued 0% Fed rate policy. That's driving the ratio. Banks are still awash in cash and cheap money from the Fed and the Fed's policy of keeping rates low for an extended period of time is going to drive this ratio higher.

It's still hard to recommend putting money into anything longer-term than a 12-month CD, especially with soaring equity markets and signs that the economy may be coming back to life. For those worried about interest rate risk, cd laddering may be a good way to smooth out the return you receive from your CD portfolio.

Mortgage Rates

Mortgage rates have declined over the past three weeks, touching lows not seen since last April when the Fed began buying up mortgage backed debt. According to the BestCashCow rate tables, the average 30-year fixed rate mortgage is now below 5% at 4.901%. The fifteen-year fixed rate mortgage average is 4.373%, close to the all-time low.

What one hand giveth, the other taketh. And so it is that savers are subsidizing borrowers. I could provide a scathing commentary on this but will simply say that if you can't beat them, join them. If you are looking to buy or refinance, now is another great opportunity to do so. You can compare the best mortgage rates in our new Mortgage section.

alt

Savings, CD, and Mortgage Rates Hit Record Lows - Weekly Rate Update

Rate information contained on this page may have changed. Please find latest savings rates.

Savings rates stayed at the 52-week low last week, holding steady at 1.61% APY. One year CD rates took the steepest dropped by 1 basis point to a new BestCashCow low of 2.00% APY. According to the BestCashCow mortgage rate tables, the average 30-year fixed rate mortgage is below 5% at 4.957%. The fifteen-year fixed-rate mortgage average is 4.4%.

The Labor Department provided an early Holiday present today, providing a job's report that was far better than anyone expected. Yes, the economy still shed jobs, but only a seasonlly adjusted 11,000 in November versus projections of 100,000. The unemployment dipped for the first time in months, going from 10.2% to 10%. The employment news caused the dollar to strengthen and gold to plunge on expectations that the Fed may begin raising rates sooner than expected. Ironically, this has happened at the same time that savings rates, cd rates, mortgage rates, and muni bond rates are hitting multi-year lows. Coincidence? Probably not. The economy seems to have bottomed and rates are a lagging indicator. For savers, the night is darkest just before the dawn, and we may be seeing the faint glimmers of sun. For borrowers, the golden days may be coming to an end. If you were thinking of refinancing or buying a home, now is the time. Mortgage rates are at record lows and if the economy continues on its current trajectory, will begin rising soon.

CD and Savings Rates

Savings rates stayed at the 52-week low last week, holding steady at 1.61% APY. One year CD rates took the steepest dropped by 1 basis point to a new BestCashCow low of 2.00% APY. Three year rates actually rose by 8 basis points from 2.72% APY to 2.8% APY due to the addition of several new banks to the rate tables with aggressive pricing. Five year rates also increased by 2 basis points to 3.35% APY.

Looking at the yield ratio we have developed for deposit accounts, the spread the spread between savings rates and 36-month CDs reached a new all-time high. As we discussed, 3 year (36 month) CD rates rose due to aggressive pricing from several banks new to the rate tables. Nevertheless, the fact remains that longer-term CD continue to inch up even as savings rates remain steady or decline. If the economy continues to firm up, look for 3 and 5 year CD rates to continue rising and the ratio to go even higher.

It's still hard to recommend putting money into anything longer-term than a 12-month CD, especially with soaring equity markets and signs that the economy may be coming back to life. For those worried about interest rate risk, cd laddering may be a good way to smooth out the return you receive from your CD portfolio.

Mortgage Rates

Once again, savers' pain is a borrower's gain. Mortgage rates again hit record lows over the past week. According to the BestCashCow rate tables, the average 30-year fixed rate mortgage is below 5% at 4.957%. The fifteen-year fixed-rate mortgage average is 4.4%.

MortgageRateAnalysis

You can compare the best mortgage rates in BestCashCow's new mortgage section.


Bank Saver Update - Impact of Shutdown on Deposit Rates

Rate information contained on this page may have changed. Please find latest savings rates.

Short term CD and online savings accounts continue to fall while longer-term CD rates continue their climb, even in the face of the budget standoff and threat of default. The rise in longer-term rates is good news and shows that bankers expect rates to continue to rise and consumers are demanding more yield to lock their money up for an extended period of time.

From one month ago, 12 month average CD rates decreased by two basis point from 0.351 to 0.349% APY. After increasing before the budget battle, average 3 year CD rates dropped from 0.715 to .714% APY. Five year average CDs continued their march upward, moving from 1.073% to 1.079% APY, up from their low of 1.049% APY in June. The biggest loser over the past month have been online savings account average rates, which fell from 0.681% to 0.664% APY. Online savings accounts have been the bright spot of the last couple of years, retaining relatively high rates even while CD rates crashed. Short term savings vehicles like online savings accounts and one year CDs continue to fall, showing that in the short-term, banks believe rates will stay low.

* * * *

Keep track of deposit rates

If you have not already, sign up for the BestCashCow Weekly Rate Update Newsletter and get the best rates from your state or from around the country delivered right to your email box. It's free and takes 30 seconds to do. Sign up.

* * * *

The chart below shows the trend in average rates since October 2012.

Top Rate Recap

During this period, top savings and CD rates stayed pretty much status quo.

  • Online Savings: GE Capital Bank retains the top spot at 0.90% APY.
  • 1 Year CD: Nationwide Bank holds the top spot at 1.06% APY with a $100,000 minimum balance. GE Capital Bank is right below it with a 1.05% APY rate and a smaller $500 minimum balance.
  • 3 Year CD: Pentagon Federal Credit Union has taken the top spot with a 1.51% APY CD. Last month, the best rate was 1.50% APY from Salem Five Direct.
  • 5 Year CD: iGoBanking.com continues to offer a 2.05% APY CD.
  • Rewards Checking: Hope Credit Union and Money One Federal Credit Union both have the top rewards checking rate of 3.01% APY for balances up to $10,000. Both credit unions are open to members from across the country.

It's possible to find even better rates at local banks and credit unions (especially for CDs). You can search for better local rates here.

Online Saving and CD Spread

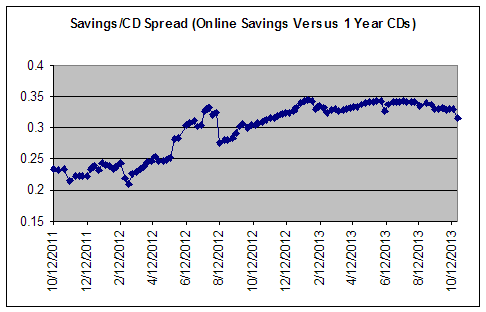
The difference between average 1 year CD rates and average online savings rates continued to decline from the high it achieved in May 2013. On average, online savings account rates pay 0.315 percentage points more than 1 year CDs, up from 0.23 percentage points more at the beginning of last year but down from the spread's high of 0.344 percentage points in May. In addition to paying more than 1 year CDs, online savings rates pay almost the same as 3 year CDs. Despite the fact that online savings rates have lost some ground to 1 year and 3 year CDs, in a rising rate environment, it makes more sense to stay liquid with an online savings account than to lock money into a low rate CD. If the spread declines dramatically then this may be worth revisiting.

General rate environment

As I wrote on the eve of the government shutdown:

"The shutdown provides another tailwind to an economic recover, slowing the economy, and depressing both deposit and borrowing rates. The longer the shutdown, the stronger this tailwind."

Consumer confidence took a significant hit from the government's, with the guage taking its most significant downturn since the collapse of Lehman Brothers in 2008.

Standard and Poor estimated that the shutdown cost the United States $23 billion. The combination of the drop in consumer confidence and the hit to the economy have slowed growth. All of this serves to prolong the Fed's bond buying and the low interest rate environment we are currently in.

In the past, I've identified 4 factors that will impact the timing and scope of interest rate increases:

  • Government & Taxes
  • Europe's economic future
  • Technology
  • General economic baselines (this encompasses consumer confidence)

Any of these can contribute or subtract from growth. Right now, government policies and employment are acting as a drag on the economy.

Still, despite this bump in the road, all signs point to the economy gaining momentum through the end of this year and into next year. I do believe that this economic upturn is real and that rates will continue to slowly rise from this point (even though the Federal government is doing its best to botch the recovery).

So if we look at the scorecard:

  • Taxes & Government: Increasing - drag on growth. Negative
  • U.S. economic growth: Slow to moderate. A protracted fight on the debt ceiling has hit growth and lowered rates. While this was improving last month this month we'll call it: Neutral.
  • Europe and the world: Europe leaving recession; Japan strong growth; developed world slowing but still growing. Overall, world picture is improving. Positive
  • Technology: Gas prices at the pump coming down and plentry of natural gas for the cold winter months due to fracking and other extraction innovations. Slightly Positive.

My outlook: The government shutdown and default embroglio have taken some wind out of the economies sales. Still, as long as the politicos are not back at it in 3 months the damange should be relatively short. Short term rates will continue to fall for a bit longer even as longer term rates continue to rise. The Fed will increase the Federal Funds rate within the next 14 months. Savings rates will hover in the 2-3% range by the end of next year.

Savings Accounts or CDs?

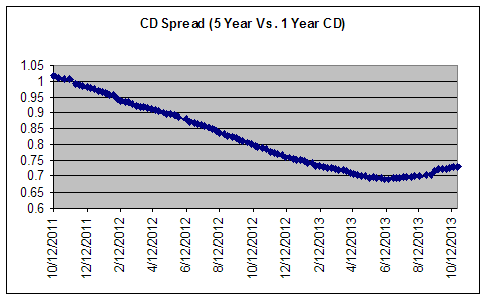
The data continues to show that opening a savings account is a better bet than a 1-3 year term CD and I expect this to hold through 2013. Online savings accounts have held the line over the past year and even though CD rates have stabilized and ticked up, the premium is still not enough to jusity locking the money away. While the premium for opening a 5 year CD over a 1 year CD has increased over the past six weeks, it is still only at 0.722 versus over 1 percentage point in October 2011. In a rising rate environment, it does not make sense to tie up money for 5 years with only a 30 basis premium.

Is it worth it to go long and open a 5 year? I don't think so any more. I think the 5 year CD rates are just too low and that you'd be better off putting your "safe" money into an online savings account and waiting for rates to rise. I spoke to one banker several weeks ago who said that "no one was investing in long-term CDs." Keep your powder dry.

For money you want to keep liquid, go with online savings accounts. They offer better rates than 1-3 year CDs and athough several banks have dropped rates in the past month, they have still offered decent rate stability over the past year and a half.

Make the best of a tough savings situation in 2013

Yields may be low in 2013 but a savvy saver can boost the return with no increase in rate by rate shopping. By shopping around, a saver can earn an extra half to full percentage point. On $100,000, that's $1,000 in extra cash per year. Remember, even in today's environment, there is competition for your cash.

Get Our Weekly Rate Update E-mail Newsletter

If you haven't already, sign up for the BestCashCow Weekly Rate Update Newsletter and get the best rates from your state or from around the country delivered right to your email box. It is free and takes 30 seconds to do. Sign up.