
American Flag

Best Online Savings & Money Market Account Rates 2026

Best Online Savings & Money Market Account Rates

Recent Articles


Mainstream Media Catching on to Raging Bank Rate War

Rate information contained on this page may have changed. Please find latest savings rates.

The mainstream press is catching on to something we've been writing about for some time, namely that banks are being forced to keep their rates high to prevent runs and to rebuild liquidity.

The Wall Street Journal published an article today entitled Banks Wage Rate War for Deposit (subscription required).

For those of you who read BestCashCow, the article won't come as a surprise. It discusses how banks, strapped for deposits and fighting to maintain liquidity and prevent bank runs have had to raise rates to keep and attract deposit dollars, your dollars. Past BestCashCow articles on this include:

From the WSJ article:

"Banks covet deposits because of this year's failures of IndyMac Bank, Washington Mutual Inc.'s banking operations and other institutions. Bank executives have been rattled by those seizures and the woes of beleaguered banks such as Wachovia Corp. and National City Corp., from which panicky customers yanked their money. Many lenders are now ratcheting up rates to shore up their deposits."

And:

"The desire to lure depositors is triggering a "national price war," says Michael Poulos, a partner at financial-services consulting firm Oliver Wyman. "In the past 15 years, there's been nothing like this. The level of competitive intensity is unprecedented right now."

Even though rates have held up well despite cuts in the Fed Funds Rate, BestCashCow data shows that they may have peaked and have declined from their high. Whether they continue to decline depends on whether the Fed cuts rates further and how much additional stress banks face in the next six months.

Below is an analysis of savings account rates compared to Certificates of Deposit.
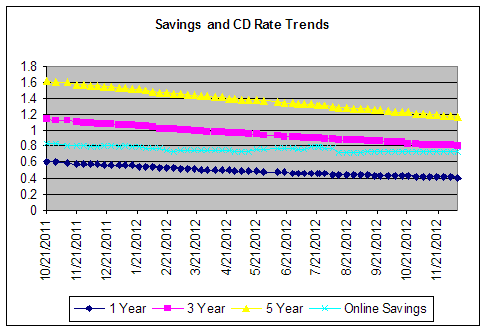
Savings and CD Rate Analysis

Even if they do decline, I still expect that we'll see a premium over the Fed Funds rate for some time. The collapse of Wall Street is the collapse of a financial model that generated lots of cheap capital and liquidity. It fueled enormous bank and financial profits. But the model has been proven faulty and as banks go back to the basics - borrowing from consumers and lending out their money - they are going to have to pay more for our money.

Now, we'll see how long it takes for banks to begin offering toasters, televisions, and trips to Florida to get your cash. There is now more competition than ever for your money, and on BestCashCow we think that's a good thing. Make sure you are getting the highest rate.

Prospect Mortgage to Acquire IndyMac Mortgage Branches

Prospect Mortgage issued a press release yesterday saying it was acquiring Indymac's retail mortgage branches. The release reads in part:

(Northbrook, IL, July 8, 2008) – Prospect Mortgage has signed an agreement to acquire the majority of IndyMac Bankcorp’s retail mortgage branches. Terms of the transaction were not disclosed.

The transaction encompasses approximately 750 employees along with more than 60 branch offices which will rebrand as Prospect Mortgage. John Johnston and Ron Bergum will remain in leadership roles with the retail branch group and report to Mark Filler, CEO of Prospect Mortgage.

I spoke with Prospect Mortgage and this transaction just covers Indymac's mortgage business. They are not purchasing other bank functions or the bank's deposit business. Indymac has stated that it plans to exit the retail mortgage business and this looks like a logical step.


How Bank Failures in 2008 Compare to Tough Times in 1980's - Updated

Last July I compared bank failures in 2008 to bank failures during the S&L Crisis in the late 1980s. At the time, Indymac has just failed and many hoped the banking system would stabilize. Then came Fannie, Freddie, Lehman, AIG, WaMu, Wachovia, Citi, Merrill...

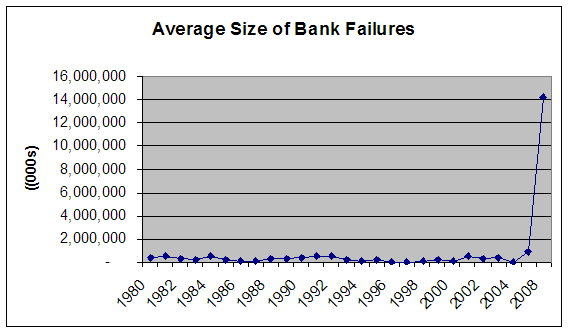
The data now shows that the financial crisis far exceeds anything that occurred in the 1980s.

While there have only been 24 failures so far, they have accounted for $341,000,000,000 in assets, far above the $164,000,000,000 in assets for failed banks in 1989. Consolidation has played a big part of this. There are 50% fewer banks today than there were 10 years ago. By any measure, this banking crisis is much more massive than what happened in the late 1980s.

This credit crisis has also impacted the biggest of the financial institutions. Many of the biggest banks took enormous gambles on mortgage related securities and held assets that turned toxic once the mortgage market turned down. When the best turned bad, these toxic assets dwarfed their capital, leading to rating downgrades, which led to investor and depositor flight, which led to insolvency. Leverage can create enormous gains in good times but it can also result in staggering losses in bad times. Big banks, which previously seemed like pillars of stability in bad times were swept away.

A look at the charts shows that in the 1980s, bank failures did not spike in one year and then come back down, but rather remained elevated for an extended period from 1988 - 1993. It's possible that the TARP will prevent further bank failures but don't count on it. Treasury Secretary Paulson said that the TARP was not meant to rescue every bank. With real estate values continuing to fall, I imagine we'll see the FDIC setting up more shotgun bank marriages a la WaMU/Chase and Wachovia/Wells Fargo in 2009. Who the government will let live and who will be allowed to go under will be an interesting policy question for the new administration.

This data was taken from the FDIC's failed bank list. The list includes Washington Mutual, which was purchased in distress by JP Morgan Chase. But it does not include Wachovia, purchased under similar circumstances by Wells Fargo or Countrywide, acquired by Bank of America.. It also doesn't include Citigroup, which would have failed were it not bailed out by the government or any of the non- FDIC regulated financial companies that were bailed out, that failed, or were purchased in distressed condition - Fannie Mae, Freddie Mac, AIG, Lehman, Bear Stearns, Merrill Lynch. Even without the inclusion of these institutions, it's clear that 2008 will be a year that the banking world will be happy to put behind.