dollars image

1-Year CD Rates from Online Banks 2026

1-Year CD Rates from Online Banks 2026

Recent Articles


Where to Find the Best Deposit Rates

Rate information contained on this page may have changed. Please find latest cd rates.

I occasionally like to analyze the BestCashCow database to see how rates vary by state, bank size, etc. It's been awhile since I ran a rate analysis by bank size and by bank type (online versus brick-and-mortar) so I decided to update it and see how various sized banks fare against each other and against online banks and credit unions. If you want a competitive rate should you start at the big bank down the street, the credit union, or the small local bank? Or should you open an online account? Here's what I found.

Smaller Banks Offer Higher Rates

For those who prefer brick-and-mortar banking an analysis of over 6,000 banks revealed that you can earn almost half a percentage point more on a CD just by depositing money at a small community banks versus a big mega-bank. Or, put another way, small community banks with less than $1 billion in assets on average pay 0.40 percentage points more on a 3 year CD and 0.44 percentage points more on a 5 year CD.

These results are in-line with what we discovered last year, the findings being published in the Wall Street Journal. The bigger banks don’t want to compete on rate and prefer to compete on convenience and technology. If you are looking for a better rate it would be wise to investigate some of the smaller banks in your neighborhood.

Bigger is Better with Credit Unions

When analyzing credit unions, the finding is reversed: bigger is better, at least when it comes to CD rates. After analyzing 2,242 of the 6,753 NCUA insured credit unions, BestCashCow data shows that on average credit unions with greater than $10 billion in assets pay .30 percentage points more than those with under $1 billion in assets for 3 year CDs. The same finding holds true for 5 year CDs.

Larger credit unions operate fall smaller branch networks than a similar sized bank and in this way their cost structure is closer to online banks. They are able to take the savings from their scale and pay it out in higher rates.

Local Banks & Credit Unions Versus Online Banks

Last year, up to 8% of the banks in our database beat the best online rate in 3 year and 5 year CDs. This year, the number has shrunk to 4% as brick-and-mortar institutions have cut rates while online banks have held relatively firm. If you are looking to open a savings account, an online bank is the place to get the best rate. The same is true for 1-2 year CDs. For 3-5 year CD terms you can still find local banks that offer rates as good as if not better than that offered by an online bank. You can search for local online rates here.

Conclusion

  • If you don't mind opening an online account, the online banks offer the best rates on savings and money market savings accounts as well as 1-2 year CDs.

  • If you plan to open a 3-5 year CD, then you can choose from an online bank or a competitive local bank. The big banks are not competitive.
  • If you quality for membership, a large credit union might offer the best rates, combining the rates of an online bank with the service of a community bank.

To help you begin your search for the best rates:

Top CD Rate 3.31% APY - Savings and CD Rates Flat for Third Straight Week

Rate information contained on this page may have changed. Please find latest cd rates.

Savings and CD rates barely moved at all in the last week as the environment can best be described as flat. This marks the third week in a row that rates have barely budged. I haven't seen such a quiet period in the last two years.

Savings Rates

On the savings front, average rates stayed steady at 1.36% APY. While CNB Bank Direct dropped their online savings rate by 10 basis points from 1.35% APY to 1.25% APY, Sallie Mae Direct raised their rate from 1.25% APY to 1.40% APY. The top rates remained steady with Southern Community Bank's Ready Saver 2% APY Savings Account leading non-promo rates. For promotional rates, Everbank remains on top with their 3-month introductory bonus rate of 2.25% APY. After the three-month period, the rate drops down to 1.26% APY for a blended one year APY of 1.51% APY. Banks that dropped their rates include:

CD Rates

The average 1-year CD remained steady at 1.61% APY. First City Bank continued to hold the top spot with a 1.80% APY CD. First City Bank is in bad financial shape and has been operating under a FDIC Cease and Desist Order since 10/09. Tennessee Commerce Bank maintained the second spot at 1.70% APY.

The average 3-year CD rate also remained steady at 2.47% APY. Like last week, the top spot is occupied by USAA Federal Savings Bank, which requires a minimum deposit of $175,000. The next highest rate is Acacia Federal Savings at 2.65% APY and a $500 minimum deposit.

The average 5-year CD rate is the only one that changed at all from the previous week. It rose a miniscule 1 basis point from 3.16% APY to 3.17% APY.

USAA has the top rate at 3.31% APY. Everbank continues to have the second highest rate at 3.30% APY. versus the 3.39% APY it was offering last week.

The Fed and Interest Rates

Rates are stuck between the Fed's direction and the recovering economy. Last week, at the Fed's FOMC they reiterated that they plan on keeping rates exceptionally low for an extended period of time.

An article in Bloomberg from two weeks ago, points out that there is no evidence of inflation on the horizon and if anything, deflation is a bigger concern.

"Demand for U.S. government bonds is increasing. On average, the Treasury received $3.21 in bids for each dollar sold at 10- year auctions this year, compared with $2.63 in 2009 and $2.41 from 2004 through 2008, according to data compiled by Bloomberg.

“Part of what’s frustrated bond vigilantes has been that economic data has ratified the notion of modest growth and continued declining inflation,” said Wan-Chong Kung, a money manager who helps oversee $89 billion at FAF Advisors in Minneapolis, the asset-management arm of U.S. Bancorp."

At the same time, GDP readings for the first quarter have come back strong and just today, the government announced that manufacturing grew in April at the fastest pace since 2004.

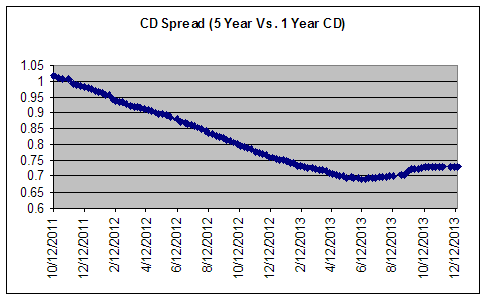
The chart below shows that while the spread between different deposit accounts is still high but is no longer going up. It refleclts the lack of change in any of the rates we have been following over the past three weeks. Perhaps the Spring weather has distracted bankers or maybe everyone is on the fence, trying to decide which wasy the economy, inflation, and rates are headed.


3-Year CD Rates Biggest Loser - Top CD Rate Steady at 3.41% APY

Rate information contained on this page may have changed. Please find latest cd rates.

Another week, another drop in CD rates. As the Fed wishes, so it gets. All terms of CD rates were down and some of the top rates fell from their perch this week as the trend was down, down, down. As we've seen lately, longer-term (5-year) CDs fell less than their shorter-term cousins and as a result the spread between 5-year and 1-year CDs hit a new record high.

The average 1-year CD dropped by 3 basis points from 1.39% APY to 1.36% APY. The top rate also dropped from 2% last week to 1.80% APY from First City Bank. First City Bank is in bad financial shape and has been operating under a FDIC Cease and Desist Order since 10/09. Southern Commerce Bank has the next highest rate at 1.75% APY but as the BestCashCow rate tables show, it also has some financial problems.

If you stay below FDIC limits you will not lose your principle, but if a bank goes under the FDIC or the bank that assumes deposits has the ability to reset these deposit rates. Thus, a high rate CD can be reset to a lower rate. The assuming bank does provide customers with the option of withdawing funds in that case. With rates so low though, a rate reset wouldn't be devestating. It's depositors who opened CDs several years ago when rates were above 5% who really suffer when the bank fails and rates are reset down to 2% or lower.

The average 3-year CD rate was the big loser this week, falling 6 basis points from 2.58% APY to 2.52% APY. USAA Federal Bank Savings Bank cut their rate, leaving Bank United in the top spot with a 2.75% APY CD. Bank United is not yet rated because it is a relatively new banking entity, having emerged from the ashes of the old, failed BankUnited. The new bank has been recapitalized and appears to be in much better financial shape than it predecessor.

The average 5-year CD dropped by only 1 basis points to 3.19% APY. The top rates have also remained steady or even increased slightly..

USAA continues to have the top 5-year CD rate at 3.41% APY but it does have that $175,000 minimum balance. Everbank has the second highest rate at 3.39% APY up from 3.33% APY last week. One thing to note about Everbank is their penalty for breaking a CD early. According to their terms:

"This penalty will be equal to one-fourth of the total interest that would have been earned on the principal balance of the account if funds had not been withdrawn prior to the maturity date." On a 5-year, 60 month CD, that's 15 months of interest.

The spread between average savings rates and 3-year CD rates has trended down over the past four weeks, mainly because 3-year CDs have dropped faster than savings account and money market rates. The opposite is happening with 5-year CDs, which have remained firm. The spread between 1-year CDs and 5-year CDs hit another record high last week. You can now earn on average 1.55% APY more in a high yield 5-year CD than a high yield 1-year.