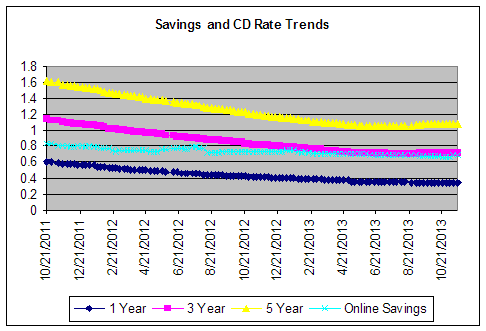
The rally that we saw in CD rates over the past four months appears to have pretty much exhausted itself. Short term and long term CD rates have remained flat over the past month. Online savings account averages have bumped up a bit as several banks have raised rates. The recent budget battles, botched health care roll-out, and signals from Fed Chairmwoman-to-be Janet Yellen that she plans to keep rates low have all contributed to squelching the mini rally we saw in the spring and summer.
From one month ago, 12 month average CD rates decreased by one basis point from 0.349 to 0.348% APY. Average 3 year CD rates dropped from 0.714 to .713% APY. Five year average CD rates remained flat at 1.079% APY. Online savings accounts averages moved from 0.664% to 0.685% APY.
* * * *
Keep track of deposit rates
If you have not already, sign up for the BestCashCow Weekly Rate Update Newsletter and get the best rates from your state or from around the country delivered right to your email box. It's free and takes 30 seconds to do. Sign up.
* * * *
The chart below shows the trend in average rates since October 2012.
Top Rate Recap
During this period, top savings and CD rates stayed pretty much status quo.
- Online Savings: GE Capital Bank retains the top spot at 0.90% APY.
- 1 Year CD: GE Capital Bank has moved into the top spot with a 1.05% APY rate, replacing Nationwide Bank that had a 1.06% APY rate but with a $100,000 minimum balance.
- 3 Year CD: Pentagon Federal Credit Union has increased its rate to 2.02% APY, with the next closest rate being CIT Bank at 1.40% APY (thanks to Shorebreak for alerting us on the rate increase with PenFed).
- 5 Year CD: CIT Bank moves into the top spot with a 2.05% APY CD, replacing iGoBanking.com, which had a 2.05% APY rate also but has dropped its rate down to 1.65% APY.
- Rewards Checking: Hope Credit Union and Money One Federal Credit Union both have the top rewards checking rate of 3.01% APY for balances up to $10,000. Both credit unions are open to members from across the country.
It's possible to find even better rates at local banks and credit unions (especially for CDs). You can search for better local rates here.
Online Saving and CD Spread
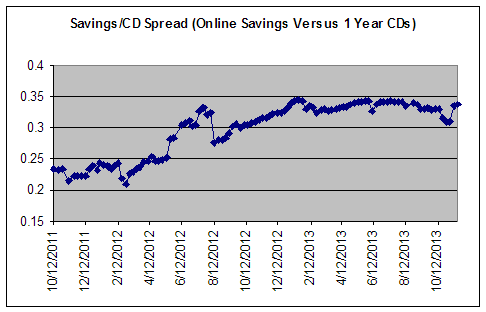
The difference between average 1 year CD rates and average online savings rates spiked up over the last two weeks with the increase in online savings account averages. As the chart below shows, the difference between online savings accounts and CDs has remained relatively consistent over time. It's my opinion that online savings accounts represent the best place to park your cash at the moment, as they offer a high rate, relative rate stability, and liquidity should rates begin to rise in the future. Certificates of deposit just do not pay enough premium to justify keeping money locked in them.
General rate environment
The shutdown augered the start of a slow patch in the economy. That, combined with the botched healthcare rollout have stolen the headlines and taken some of the wind out of the sale of consumer confidence. Maybe someday, the government will get out of its own way.
Janet Yellen, nominated to succeed Ben Bernanke as the next Chairperson of the Fed also made it clear that she will continue the quantitative easing program. The result has sent the Dow soaring and put a further damper on any rate gains for longer-term instruments. In addition the Euro-zone reported slowing growth, further depressing growth prospects for the global economy and demand for U.S. goods and services.
At this point, any economic uptick is obscured by all of this other noise. It will be interesting to see how sales come in this Holiday season. A blockbuster season woutl auger well for economic growth. Still, I remain optimistic that economic growth has not stalled out and that once the dust settles from the shutdown and bickering in D.C., the debut of Obamacare, and Ms. Yellen's arrival (assuming she is confirmed) some sense of growth and optimism will return.
So if we look at the scorecard:
- Taxes & Government: Increasing - drag on growth. Negative
- U.S. economic growth: Slow to moderate. A protracted fight on the debt ceiling has hit growth and lowered rates. While this was improving last month this month we'll call it: Neutral.
- Europe and the world: Europen and Japanese growth slowing. China prospects improving. Overall, world picture is improving. Neutral
- Technology: Gas prices at the pump coming down and plentry of natural gas for the cold winter months due to fracking and other extraction innovations. Slightly Positive.
My outlook: The government shutdown and default embroglio and healthcare rollout have taken some wind out of the economies sales. Still, as long as the politicos are not back at it in 3 months the damange should be relatively short. Short term rates will continue to fall for a bit longer even as longer term rates continue to rise. The Fed will increase the Federal Funds rate within the next 14 months. Savings rates will hover in the 2-3% range by the end of next year.
Savings Accounts or CDs?
The data continues to show that opening a savings account is a better bet than a 1-3 year term CD and I expect this to hold through 2013. Online savings accounts have held the line over the past year and even though CD rates have stabilized and ticked up, the premium is still not enough to jusity locking the money away. While the premium for opening a 5 year CD over a 1 year CD has increased over the past six weeks, it is still only at 0.722 versus over 1 percentage point in October 2011. In a rising rate environment, it does not make sense to tie up money for 5 years with only a 30 basis premium.
Is it worth it to go long and open a 5 year? I don't think so any more. I think the 5 year CD rates are just too low and that you'd be better off putting your "safe" money into an online savings account and waiting for rates to rise. I spoke to one banker several weeks ago who said that "no one was investing in long-term CDs." Keep your powder dry.
For money you want to keep liquid, go with online savings accounts. They offer better rates than 1-3 year CDs and athough several banks have dropped rates in the past month, they have still offered decent rate stability over the past year and a half.
Make the best of a tough savings situation in 2013
Yields may be low in 2013 but a savvy saver can boost the return with no increase in rate by rate shopping. By shopping around, a saver can earn an extra half to full percentage point. On $100,000, that's $1,000 in extra cash per year. Remember, even in today's environment, there is competition for your cash.
Get Our Weekly Rate Update E-mail Newsletter
If you haven't already, sign up for the BestCashCow Weekly Rate Update Newsletter and get the best rates from your state or from around the country delivered right to your email box. It is free and takes 30 seconds to do. Sign up.