Best Online Savings & Money Market Account Rates 2026
Best Online Savings & Money Market Account Rates
Recent Articles
Top Savings Rate Stays at 2% - Average Down to 1.4% APY
Rate information contained on this page may have changed. Please
find latest savings
rates.
Author:Sol Nasisi
on March 16, 2010
- modified on October 11, 2018
Savings rates dipped very slightly this past week with the average dropping from 1.41% APY to 1.40% APY. Despite this drop, the top savings rate remained at 2% (ReadySaver.com from Southern Community Bank). Everbank also continued to offer their promo rate of 2.25% APY for the first three months on new money. After three months, the rate drops to 1.26% APY for a 1-year blended APY of 1.51%.
Savings rates dipped very slightly this past week with the average dropping from 1.41% APY to 1.40% APY. Despite this drop, the top savings rate remained at 2% (ReadySaver.com from Southern Community Bank). Everbank also continued to offer their promo rate of 2.25% APY for the first three months on new money. After three months, the rate drops to 1.26% APY for a 1-year blended APY of 1.51%.
Other notable rates include Franklin Synergy Bank at 1.75% APY and EBSB at 1.67% APY.
For those of you looking to deposit your money into a larger bank, student lender Sallae Mae just opened an Internet bank and is offering a 1.25% APY savings account. It was 1.35% APY last week. American Express Federal Bank is offering a 1.30% APY.
The table below shows the trend with savings rates as well as select cd rates. For savings, the trend is generally down.
Savings and CD Rates Continue to Drop - Weekly Rate Update
Rate information contained on this page may have changed. Please
find latest savings
rates.
Author:Sol Nasisi
on February 2, 2010
- modified on October 11, 2018
Most savings and CD rates hit record lows last week. Average savings rates reached a new record low of 1.47% APY last week, down 4 basis point from 1.51% APY the previous week. Average one-year cd rates showed the largest drop, falling 10 basis points to 1.85% APY. Average three-year cd rates dropped four basis points to 2.63% APY. The only glimmer of good news were five-year CD rates which increased from 3.18% APY to 3.20% APY.
The two big news events over the last week were the Federal Open Market Committe statement, in which the Fed committed to keeping rates low for the foreseeable future and for kind've slowing its purchase of mortgage backed securties and President Obama's whopping $3.8 trillion budget.
The Fed, as it has for the last year, committed to keeping the Fed Funds rate pegged close to 0%. At the same time, the Fed said that it was beginning to slow its purchase of mortgage backed securities.
" To provide support to mortgage lending and housing markets and to improve overall conditions in private credit markets, the Federal Reserve is in the process of purchasing $1.25 trillion of agency mortgage-backed securities and about $175 billion of agency debt. In order to promote a smooth transition in markets, the Committee is gradually slowing the pace of these purchases, and it anticipates that these transactions will be executed by the end of the first quarter. The Committee will continue to evaluate its purchases of securities in light of the evolving economic outlook and conditions in financial markets."
That's the way to sit on the fence.
I've been expecting mortgage rates to begin to rise with this announcement but the opposite has happened over the last month. After peaking at close to 5.2% in late December, mortgage rates have come down and are now once again below 5%. This is a gift for those that want to purchase or refinance a home.
Many still predict that as the Fed lays off the MBS juice, mortgage rates will begin to go higher.As I wrote last week, low rates are both a benefit and a boon. You'll have to decide if getting a low rate is worth the risk that your house will lose value once rates start to move up.
President Obama's budget is also front and center to our rate discussion. $3.8 trillion is a lot of money and the budget shortfall is expected to reach a record $1.6 trillion in 2010 with whopping deficits going out beyond the horizon. What does that mean? More issuance of Treasuries. Eventually the market will be flooded with US debt and unless corrective action is taken, which seems doubtful, we're all looking at longer-term interest rates.
Right now though, higher interest rates would be welcome news for the savers of the world.
CD and Savings Rates
Most savings and CD rates hit record lows last week. Average savings rates reached a new record low of 1.47% APY, down 4 basis point from 1.51% APY the previous week. Average one-year cd rates showed the largest drop, falling 10 basis points to 1.85% APY. Average three-year cd rates dropped four basis points to 2.63% APY. The only glimmer of good news were five-year CD rates which increased from 3.18% APY to 3.20% APY.
Like the Treasury yield, BestCashCow has developed its own yield ratio for deposit accounts (a short duration deposit account) and 3 year CDs. As the chart below shows, the yield has been on the rise and is currently at 1.16. This is the second highest reading since we began compating this data. The yield ratio continues to mimic the Treasury yield curve, which is low on the short end and rises on the long-end.
At this point it's still hard to recommend putting money into anything longer-term than a 12-month CD, especially with rising rate risk. CD laddering may be a good way to smooth out the return you receive from your CD portfolio. Several banks have come out with breakable CDs, that allow users to withdraw money penalty free, and still other banks are lowering the withdrawal penalty, as Ally Bank recently did, for removing money before maturity.
Savings Rates and CD Rates Little Changed - Weekly Rate Update
Rate information contained on this page may have changed. Please
find latest savings
rates.
Author:Sol Nasisi
on February 17, 2010
- modified on October 11, 2018
Savings rates and CD rates were little changed from a week ago, with rates moving 1 or 2 basis points for the various products. The top rates for various cd terms and savings accounts were unchanged from a week ago. The spread between short term and longer term deposit accounts remained elevated.
Last week the Fed gave its first indication that it might start raising rates sometime in the future. Bernanke stated that the Fed may raise the Discount Rate before long. The discount rate is the rate at which banks can take emergency loans from the Fed. It is not the same as the Federal Funds rate, which is more influential in impacting interest rates. Still, it's a start.
Over the past week, the issue of sovereign government default became more prominent as Greece jockeyes for a bailout from the EU. Many believe that Greece's debt problems are just a prelude to more problems from other highly indebted nations - Spain, Ireland, Italy, Japan. And some, like Marc Faber believe that mounting debt levels could even impact the United States.
A Federal Funds Rate predictions chart would show that markets do not anticipate a rate increase through the June Fed meeting. I suspect the rate will stay pegged at 0-25% a good deal longer, and potentially through the rest of 2010.
A low Fed Funds Future rate means low rates on savings accounts, money markets, and certificates of deposit for a good deal longer.
Savings Rates
Average saving rates hit a record low again last week moving from an average rate of 1.46% APY to 1.45% APY. While the averages have come down, the highest rates on the BestCashCow rate tables have remained steady. The highest rate is the Everbank Money Market Account, which is offering a 3-month guaranteed promo rate of 2.25% APY. The 1-year APY for the account is 1.51%. Following that is Franklin Synergy with a 1.75% APY and EBSB with a 1.67% APY. Other attractive CD rates are CNB Bank Direct at 1.50% APY and American Express Bank, FSB also at 1.50% APY.
CD Rates
Both the average 1-year CD rate and the average 5-year CD rate rose slightly over the past week while the average 3-year CD rate fell slightly.
The average 1-year CD rate rose by 1 basis point from 1.82% APY to 1.83% APY. The top rate continues to be 2% APY offered by Southern Commerce Bank.
The average 3-year CD rate fell by 1 basis point from 2.61% APY to 2.60% APY. The good news is that most of the rate leaders on the table remained stable. The top 3-year CD rate continues to be 2.8% APY offered by Hudson City Bank.
The average 5-year CD rate rose from 3.29% APY to 3.31% APY. The top rate continues to be iGOBanking's 3.55% APY CD. Acacia Federal Savings Bank also has a competitive IRA only CD paying 3.50% APY. The next best 5-year rate is Everbank at 3.37% APY. This marks the third week-in-a-row that 5-year CD rates have moved up.
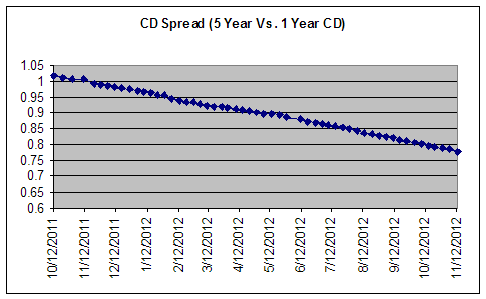
Both the cd spread and the savings/cd spread remain near record highs. What does that mean? It means as a depositor, you are being compensated more highly for putting your money into a longer-term deposit account then you were even a year ago. This isn't a suprise as savings rates have collapsed while longer-term CD rates have come down much more gradually.
As we discussed last week, the elevated ratio means it may be worth taking a look at a longer-term CD, especially one that doesn't have an onerous early-withdrawal penalty. You can now earn 1.5 percentage points more by opening a 5 year CD versus a 1-year CD. If interest rates stay low for the next couple of years, as is possible, then perhaps this elevated spread makes opening the account worth it.
Regardless of this analysis, CD laddering may be a good way to smooth out the return you receive from your CD portfolio. Several banks have come out with breakable CDs, that allow users to withdraw money penalty free, and still other banks are lowering the withdrawal penalty for removing money before maturity.