American Flag

Best Online Savings & Money Market Account Rates 2026

Best Online Savings & Money Market Account Rates

Recent Articles


The Fed Raises the Discount Rate to 0.75% - Not a Sign of Tightening

Rate information contained on this page may have changed. Please find latest savings rates.

The Fed today released a statement saying that it was raising the Discount Rate, the rate it charges banks for overnight loans, from .50% to 0.75%. This change was expected and the Fed was careful to point out that it still expects to keep the more influential Fed Funds rate low for some time.

Here's the statement from the Fed on how the rate change will impact consumer interest rates:

"Like the closure of a number of extraordinary credit programs earlier this month, these changes are intended as a further normalization of the Federal Reserve's lending facilities. The modifications are not expected to lead to tighter financial conditions for households and businesses and do not signal any change in the outlook for the economy or for monetary policy, which remains about as it was at the January meeting of the Federal Open Market Committee (FOMC). At that meeting, the Committee left its target range for the federal funds rate at 0 to 1/4 percent and said it anticipates that economic conditions are likely to warrant exceptionally low levels of the federal funds rate for an extended period."

As this article points out, the discount rate is not as influential as the Fed Funds rate in impacting interest rates and monetary policy. Nevertheless, there was a reaction in financial markets today. The dollar spiked and stocks retreated while in bond markets, Treasury prices fell and yields moved higher. These are all typical responses to anticipated higher interest rates.


Savings Rates At 2% - CD Rates Above 3.5% - Weekly Rate Update

Rate information contained on this page may have changed. Please find latest savings rates.

Average savings rates moved up slightly in the past week as several banks joined the BestCashCow rate tables with competitive rates. This included a non-promo savings rate at 2% APY. CD Rates held steady with the highest rating being a 5-year CD paying 3.55% APY. All rates are as of 2/22/2010.

Last week the Fed continued its policy of unwinding the unprecedented monetary stimulus by raising the Discount Rate from 0.50% to 0.75%. While the Fed made it clear this does not change its low rate policy, the move is still a sign that the Fed feels that the worst is behind us. The Discount Rate is the rate that the Fed charges banks for emergency overnight loans. Unlike the Fed Funds Rate, it has very little direct impact on savings, cd, mortgage rates, etc. offered by banks. The Federal Funds Target Rate remains pegged at 0-.25%.

Other relevant news includes data released by the Bureau of Labor Statistics which shows there is virtually 0 inflation even as the government floods the market with money. Inflation rose only .20% in January and almost all of that rise was due to energy costs. Core inflation, which strips out food and energy actually fell by .1%.

This data will provide no urgency to the Fed to raise the Federal Funds Rate. Their thesis of a slack market seems to be holding.

Looking at the Federal Funds Rate predictions chart, you can see that markets do not anticipate a rate increase through the June Fed meeting. I suspect the rate will stay pegged at 0-25% a good deal longer, and potentially through the rest of 2010.

A low Fed Funds Future rate means low rates on savings accounts, money markets, and certificates of deposit for a good deal longer.

Savings Rates

Average saving rates posted the first rise in 17 weeks. They rose from 1.45% APY to 1.46% APY. The increase was mainly due to the addition of three new banks to the rate, all offering competitive savings or money market accounts. These include:

  • Southern Community Bank offering a 2% APY savings account
  • Palladian Private Bank offering a 1.7% APY savings account
  • Colorado Federal Savings Bank offering a 1.4% APY savings account

Everbank still has the top rate with their 3-month promo of 2.25% APY for new money. After that, the new-comer Southern Community Bank is next at 2% APY. It's been awhile since we've seen a non-promo 2% APY rate for a nationally available account.

Other attractive CD rates are CNB Bank Direct at 1.50% APY and American Express Bank, FSB also at 1.50% APY.

CD Rates

The average 1-year CD rate rose by 1 basis point from 1.83% APY to 1.84% APY. The top rate continues to be 2% APY offered by Southern Commerce Bank.

The average 3-year CD rate rose by 2 basis points from 2.60% APY to 2.62% APY. The good news is that most of the rate leaders on the table remained stable. Hudson City Bank is the rate leader with a 2.8% APY 3-Year CD.

The average 5-year CD dropped for the first-time in four weeks, falling from 3.31% APY to 3.30% AP. Despite this, the top rate continues to be iGOBanking's 3.55% APY CD. Acacia Federal Savings Bank also has a competitive IRA only CD paying 3.50% APY. These top three rates have remained steady.

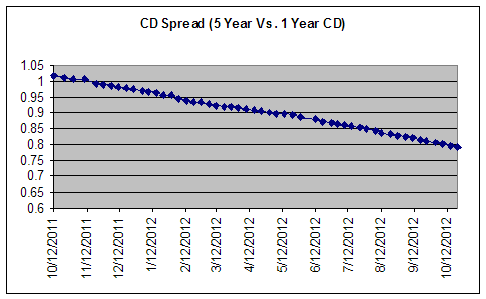
Both the cd spread and the savings/cd spread remain near record highs. What does that mean? It means as a depositor, you are being compensated more highly for putting your money into a longer-term deposit account then you were even a year ago. This isn't a suprise as savings rates have collapsed while longer-term CD rates have come down much more gradually.

As we discussed last week, the elevated ratio means it may be worth taking a look at a longer-term CD, especially one that doesn't have an onerous early-withdrawal penalty. You can now earn 1.5 percentage points more by opening a 5 year CD versus a 1-year CD. If interest rates stay low for the next couple of years, as is possible, then perhaps this elevated spread makes opening the account worth it.

Regardless of this analysis, CD laddering may be a good way to smooth out the return you receive from your CD portfolio. Several banks have come out with breakable CDs, that allow users to withdraw money penalty free, and still othe banks are lowering the withdrawal penalty (Huge Change to Ally Bank CDs Will Benefit Savers) for removing money before maturity.


Savings and CD Rates Steady - 30 Year Mortgage Rate Breaks Above 5%

Rate information contained on this page may have changed. Please find latest savings rates.

Savings and CD rates continue their slow glide to oblivion while 30-year mortgage rates climbed above 5% for the first time since October.

It's been a slow week on the economic news and rate front as bankers head for the hills and take an extended vacation. When I worked at a bank, I remember that the week between Christmas and New Years was slow. The bank was manned by a skeletal crew and for the most part, no significant decisions were made.

On the economic front, the biggest news of the past week has been the steepening of the Treasury Yield Curve to record levels. The yield is considered by many to be the most important economic indicator. My economics teacher in business school harped on its importance. The curve plots the yields of Treasury bills, notes, and bonds. A steep yield curve indicates that short term rates are low and long term rates are higher. A steep yield curve is usually a sign of an impending economic recovery as investors anticipate growth and inflation and believe longer-term rates will go up as demand for capital growns. An inverted yield curve (short term rates are equal to or higher than long-term rates) is a strong sign of a recession, since investors are betting that growth, inflation, and rates are coming down in the future.

Over the last week we experienced the steepest yield curve on record. Usually this would be a strong signal of future growth but there is a wrinkle this time. Massive government borrowing may be distorting the yield curve. Since the government needs to borrow so much money, many investors are anticipating two things: 1) inflation as the government money fuels a recovery; 2) rising Treasury rates as the government has to provide a higher rate to convince investors to soak up so much Treasury demand.

The yield curve is important for savers for several reasons. First, it directly influences the rate you'll receive on money market funds and some longer-term CDs. Money market funds invest in Treasuries and other government and municipal bonds which often take their cue from Treasuries. Second, if you invest in Treasuries, the yield on different maturities is important. Third, it provides some indication of what's going to happen in the future. Right now, the steep yield curve is indicating that rates are going up.. So, as we've said before, it might not be the best time to lock up money in a long-term CD. In 12 months you might be able to get an even better rate. Lastly, Treasury securities serve as benchmarks which help to determine mortgage rates. It's no coincidence that record low yield in Treasuries correspond to record low mortgage rates. If Treasury yields go up, so will mortgage rates.

So, what we're glimpsing in the yield curve is the eventual increase in rates for savers (good news) and the increase in rates for borrowers (not good news).

CD and Savings Rates

As long as the Fed keeps its Fed Fund rate at 0-.25% we're not going to see any significant increase in savings and CD rates. While Treasuries can serve as a forward-looking indicator, savings and most CD rates are pegged to the Fed Funds rate and not from the Treasury bond market. Savings and CD rates continue their slow glide to oblivion, although as we mentioned, rates were pretty unchanged over the past Holiday week. Savings rates stayed steady at 1.57% APY. 1-year CD rates dropped by one basis point from 1.96% to 1.95% APY. This marks the second week in a row that both savings and 1-year CD rates have not dropped or hardly dropped. 3-year CD rate rose 1 basis point to 2.66^% APY and and 5-year rates continued their recent slide, down 3 basis points from 3.21% APY to 3.18% APY.
Like the Treasury yield, BestCashCow has developed its own yield ratio for deposit accounts - the spread between savings rates and 36-month CDs. In some ways, this ratio is purer because it cannot be influenced by government debt, Fed Treasury purchase programs, and other attempts to manipulate rates. As you can see below, the ratio between savings accounts (a short duration deposit account) and 3 year CDs has dropped slightly over the past three weeks. It's still at a very elevated level though, mimicking the Treasury curve. We'll be watching how the ratio develops over the next month to see if it provides any additional clues to the state of the market in 2010.

At this point it's still hard to recommend putting money into anything longer-term than a 12-month CD, especially with rising equity markets and signs that the economy may be coming back to life. Many depositors may be willing to lock money away for 5-years at close to 3%. To me that's just not enough of a return for that period of time. For those worried about interest rate risk, cd laddering may be a good way to smooth out the return you receive from your CD portfolio.

Mortgage Rates

According to Freddie Mac's weekly survey, 30 year mortgage rates rose by 11 basis points from 4.94% to 5.05%. It's the first time since October that the average 30-year mortgage rate has gone above 5%. Data from th BedsCashCow rate tables show that average mortgage rates on 30-year mortgages (the most popular mortgage taken) shot up from 4.95% to 5.193%. This mimics the increase we've seen in longer-term Treasuries. As the Fed ends its purchase of mortgage-backed securities and Treasury securities, we'll probably see rates continue to rise. From all indications, mortgage rates are going up, which is bad for homebuyers and the general housing market.

Frank Nothaft, a Freddie Mac Vice President had this to say about rates going above 5%. "Although interest rates for 30-year fixed-rate mortgages are above 5 percent this week for the first time since the end of October, they are still around 0.5 percentage points below this year’s peak set in mid-June. ARM rates increased by a lesser amount as the market consensus calls for no rate hikes by the Federal Reserve in the immediate future."

You can compare the best mortgage rates in our new mortgage section.
