Nevada

Image Courtesy: pixabay.com


Las Vegas, Nevada 30-Year Fixed Mortgage Rates 2026

Compare Nevada 30-Year Fixed Conforming Mortgage rates with a loan amount of $320,000. Use the search box below to change the mortgage product or the loan amount. Click the lender name to view more information. Mortgage rates are updated daily.

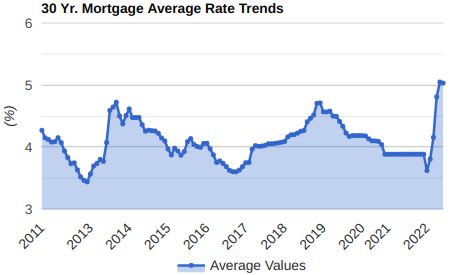
30-Year Mortgage Average Rate Trends History Chart from 2011 to 2022

Las Vegas, Nevada 30-Year Fixed Conforming Mortgage

November 9, 2026
Average: 6.78% APR
Lender APR Rate (%) Monthly
Payment?

U.s. Bank National Association


Updated 05/07/2023

6.27%

6.13%
0.63 points
$0.00 fees

$1,944.35


See Table
View   

Charles Schwab Bank, Ssb


Updated 11/06/2026

6.58%

6.25%
1.88 points
$3,210.00 fees

$1,969.25


See Table
View   

Wells Fargo Bank, National Association


Updated 09/27/2024

5.82%

6.33%
0.00 points
$0.00 fees

$1,986.77


See Table
View   

Citibank, National Association


Updated 10/18/2024

6.34%

6.58%
0.88 points
$2,739.00 fees

$2,039.06


See Table
View   

Bank Of America, National Association


Updated 05/07/2023

6.86%

6.63%
0.86 points
$0.00 fees

$2,049.00


See Table
View   

Information About Las Vegas Real Estate Market

Skip to more mortgage rates

Here are some key points about Las Vegas's real estate market:

1. Overall Market Trends: The real estate market in Las Vegas has been experiencing significant growth and stability over the past few years. Property values have been steadily increasing, and demand for housing remains strong.

2. Housing Market: Las Vegas offers a diverse range of housing options, including single-family homes, condominiums, and apartments. The city has experienced a surge in new construction, with many developers focusing on luxury properties and master-planned communities.

3. Price Growth: Home prices in Las Vegas have been rising steadily. According to recent reports, the median home price in Las Vegas is around $320,000. However, prices can vary significantly depending on the location and type of property.

4. Investment Opportunities: Las Vegas is considered a favorable market for real estate investors. The city's robust tourism industry, strong job growth, and low unemployment rates make it an attractive destination for property investments. Rental properties, in particular, have been performing well in terms of occupancy rates and rental income.

5. Competitive Market: Las Vegas experiences a highly competitive real estate market, which can result in multiple offers and bidding wars for desirable properties. It is essential for buyers to be prepared, have financing in order, and work with a knowledgeable agent to navigate through the competitive landscape.

6. Local Regulations: It is important to consider any local regulations and policies when investing in Las Vegas real estate. Stay informed about property taxes, homeowner's association fees, and any city or state-specific regulations that may impact your investment.

7. Economic Factors: The health of the local economy plays a significant role in the real estate market. Factors such as job growth, tourism, and the overall economic climate can influence property values and demand.

It is crucial to consult with a trusted real estate agent or financial adviser who specializes in the Las Vegas market to obtain up-to-date and tailored advice based on your specific circumstances and goals.

Jpmorgan Chase Bank, National Association


Updated 10/16/2026

7.21%

7.13%
0.00 points
$0.00 fees

$2,155.90


See Table
View   

Navy Federal Credit Union Credit Union


Updated 01/30/2023
Restrictions

7.43%

7.25%
0.75 points
$0.00 fees

$2,182.96


See Table
View   

Axos Bank


Updated 06/15/2022

8.40%

8.38%
0.00 points
$3,874.00 fees

$2,433.36


See Table
View   

Data provided by BestCashCow

Rates from this table are based on loan amount of $320,000 and a variety of factors including credit score and loan to value ratios. Rates may change at any time and are not guaranteed to be correct. For specific requirements please check with the lender.

PRODUCT INFORMATION

Starting Your Search for the Best Mortgage Rates 2026

Once you have found and purchased the home of your dreams, you will need to protect your investment. You will need a good understanding of the best type of loan for you as well as prevailing mortgage rates.

Securing the best mortgage isn’t simply about finding a lender who offers you the best rate. Taking out a mortgage can be a time-consuming, confusing, and even emotional process. The best mortgage lenders will guide you through the complex process with ease and treat you with respect. This makes finding the best rates from top mortgage lenders a little bit tougher than finding, say, the Best Credit Card for earning travel rewards, the Highest Yielding Online Savings Account Account or the Highest Yielding CD.

In addition to searching for the best rate, you will want to improve your credit score, identify the maximum down payment you can make and determine how long you will be in your house or apartment. Based on these factors, the following are the types of mortgage products you may wish to consider.

Fixed-rate mortgages

While fixed-rate mortgages are by far the most common type of home loan. It’s also the easiest to understand. While the proportion of your loan that is amortized will increase each month (versus interest on the balance), you still pay the same amount every month. Your interest rate is locked in when you close on the loan, so you aren’t vulnerable to sudden increases in interest rates.

Fixed-rate mortgages ordinarily require a 20% down payment (or that you pay for mortgage insurance) and are most often offered for 10-, 15- or 30-year terms, with the latter being the most popular choice. Longer terms generally mean lower payments, but they also mean it will take longer to build equity in your home. You will also pay more interest over the life of the loan.

The BestCashCow mortgage calculator is a great way to examine the amortization schedule that you will have for different fixed rate mortgage lengths and balances (hyperlink- https://www.bestcashcow.com/mortgage-calculator).

FREQUENTLY ASKED QUESTIONS

What is an adjustable-rate mortgage (ARM)?

Typically, ARMS offer lower initial interest rates, and sometimes lower initial payments than fixed rate mortgages, making it easier for a wider range of people to qualify for better homes. The interest rate remains constant for a certain period of time, most commonly 7 or 10 years although shorter and longer terms are often available. Generally, the shorter the period, the better the rate — then rises and falls periodically according to a financial index.

ARMs offer a fantastic opportunity for homeowners to get rates lower than would be available in a fixed rate product, and are ideal for those who are not planning to be in the home for more than the term for which rates are fixed, or those who will be able to pay off the mortgage should rates rise. If you don’t fit that criteria, you run that risk of your ARM beginning to adjust when interest rates are climbing in which case your payments could be adjusted upwards quite sharply. While most products have terms limited them to more than a 2% annual increase (or decrease), given that interest rates on fixed products are currently so low, you may find yourself several years out regretting that you did not lock into a fixed rate product.

What is an interest-only mortgage (IO)?

Interest-only mortgages are technically a type of ARM on which only the interest is charged each month, but the outstanding loan amount does not begin to amortize until after the interest-only period (usually 5 years). These mortgages are compelling because they allow home buyers to pay only interest for a certain period at the beginning of the loan, keeping payments as low as possible. They can be a good choice for someone who expects a significant increase in income down the pike, but they are the worst choice for those seeking to build equity in their homes. They can also lead people to mistakenly buy more expensive homes than they can afford. Once the interest-only payment period is up, your payment can jump significantly when you begin to pay the principal of the loan, plus you can experience a rate increase.

What are FHA and VA loans?

FHA and VA loans are government-backed mortgages. FHA loans require much smaller down payments than their conventional counterparts and can often be good option for those with a steady, healthy income without enough savings for a huge down payment (often as little as 2.5% down). The drawback of FHA loans is that you will likely be responsible for mortgage insurance each month in order to help the lender blunt some of the risk. VA loans are also available to those with a military affiliation and offer with low (or even no) down-payment options, minus the mortgage insurance required on FHA loans. However, the VA typically charges a one-time funding fee that varies according to down payment amount.

Products by State


10 Pros and Cons of Using A Mortgage Broker

It is common to be excited when starting the home buying process, especially for first-time homeowners. However, that excitement can quickly be taken over by confusion and overwhelm when it comes to sifting through options for the home loan. Part of the issue plaguing potential homeowners is the reality that there are tens of thousands of lenders willing and able to offer a new home loan. One of the solutions to the overwhelming number of lenders revolves around a mortgage broker.

Working as an intermediary between the homebuyer and multiple lenders, a mortgage broker helps borrowers navigate the process of getting a new mortgage from start to finish. Not only do they review financial status and credit history, but they also work through pre-approval processes, help gather the right documentation, and lend a hand with mortgage loan applications. The best mortgage brokers also offer guidance on which mortgage offer is the most suitable. While there are plenty of reasons to work with a mortgage broker, there are just as many that make homeowners avoid them as a resource. Here are the top ten advantages and disadvantages of using a mortgage broker for a new home purchase.

The Pros

1 – Comparison Shopping Made Easy

Mortgage brokers make the necessary task of comparing various lender offers a breeze. They essentially take on the brunt of the work for homebuyers, evaluating options from multiple lenders through a single source. Brokers bring homebuyers several selections based on their lender network and help guide borrowers through the terms of each.

2 – A Single Application

Mortgage applications can be long and cumbersome to complete, but with a broker, homebuyers only fill out a single application, once. The broker then reaches out to the lender network on behalf of the buyer and no additional application forms are required.

3 – Working with Poor Credit

Individuals with less than perfect credit histories or scores may benefit greatly from working with a qualified mortgage broker. Because many mortgage brokers have extensive experience in the industry, they know which lenders are more willing to make an offer to homebuyers who have had a financial misstep or two in the past. This is not often the case when working directly with a single lender.

4 – Personalized Service

Unlike big banks and national financial institutions, mortgage brokers are either individual brokers or part of a small team in most cases. This size difference lends itself to more personalized service throughout the application and closing process.

5 – Possible Reduced Costs

A mortgage broker with a long history with specific lenders may be able to save homeowners on one-time fees. Charges for applications, appraisals, origination fees, and lenders fees may be waived when working with a mortgage broker.

The Cons

1 – You Can Do it Yourself

Homebuyers have, in most cases, the same access as mortgage brokers in terms of finding different lenders and comparing mortgage loan terms. There is no reason to use a mortgage broker if you feel confident you can get the best deal on your own.

2 – A Slower Process

Because the broker does the work for the homebuyer, the total time it takes to get from application to closing can be longer than doing it on one’s own. This is because the mortgage broker shops various rates and terms behind the scenes, and it can take some time to get all the available options back to the homebuyer.

3 – Interests May Not Be Aligned

One of the biggest drawbacks to working with a mortgage broker is feeling less than confident that the individual has the homebuyer’s best interest at heart. Mortgage brokers may be paid finders fees or higher commissions with certain lenders, and less with others, but this can be difficult to ascertain as a homebuyer.

4 – Qualified Help

While there are several advantages to working with a mortgage broker, some homeowners may not know if they are receiving the most qualified help along the way. Unfortunately, some individuals holding themselves out to be qualified brokers are not, meaning they do not have a mortgage broker license or the state-required bond to go with it. Homeowners should take time to search for their mortgage broker on the NMLS database before agreeing to work together.

5 – Paying for Help

Although there are instances where mortgage brokers help save expenses for homebuyers, they do not work for free. Mortgage brokers are paid either on a commission from the lender they suggest or as a percentage-based fee of the total mortgage balance, also paid by the lender. While this is not often a charge paid for out of pocket, it is common for these fees to be rolled into the final mortgage balance owed back to the lender.

Working with a mortgage broker can be advantageous to homebuyers who want help with comparison shopping, paperwork, and finding the best deal on their new home loan. However, it is necessary to check that the broker is qualified, has access to several lenders, and does not charge excessive fees for the assistance provided.

6 Simple Ways to Pay off Your Mortgage Faster

Making monthly minimum payments on a mortgage can affect your wallet, retirement, and self-esteem. We’ll focus on the most effective mortgage repayment strategies like making initial and principal payments, and how to downsize expenses. A mortgage can be paid off in less than 7 years, but this will take some effort to understand the different strategies for how this can be done.

Quick Find Guide:

Why Should I Pay Off My Mortgage Faster?

6 Fast Mortgage Repayment Strategies:

  1. Make an Initial Payment
  2. Second Payment Towards the Principal
  3. Velocity Banking Strategy
  4. Downsize Expenses to Maximize Repayment
  5. Refinance Your Mortgage
  6. Make a Large Down Payment

Why Should I Pay off My Mortgage Faster?

Remember that initial cost breakdown of your mortgage? It probably has you paying a large sum of money towards interest (the amount of money paid to the bank for the opportunity of being given a loan). Paying off a mortgage faster will reduce the amount of money paid to interest over the term of the loan. When the principal is reduced, less interest is incurred, meaning you save money. The goal is to pay it off as fast as possible, so the money could be reinvested elsewhere.

6 Fast Mortgage Repayment Strategies

All of these strategies imply that your bank allows quicker payments and doesn’t have a prepayment penalty. If you’re unsure, contact your bank and ask them before using these methods. This is important because some banks will charge a flat or percentage-based fee for making extra payments.

In order to maximize the amount of time saved by paying off a mortgage faster, multiple strategies can be used at once.

As a way to visualize the following ways to pay off a mortgage faster, we’ll include an example that can be used for some strategies: Imply a $100,000 mortgage has a 30-year fixed rate of 4.50% APR, which has a minimum payment of $507 a month.

1. Make an Initial Payment

It may not seem like much but making a payment before your first scheduled mortgage payment can save thousands over the term of the loan. Since this payment is before any scheduled payments, it will directly go to the principal. For individuals looking to get started with real estate, this strategy is very effective and will ensure that money is saved over the long-term. Unless a lot of money is put down on the property, this strategy will only save you a few thousand. Making an initial payment of 25% of the mortgage will shorten it dramatically.

Making an initial payment with the example can save $1,448.00 and making double the initial payment can save $2,896.00. This means that the mortgage could be paid off 3 to 6 months sooner.

2. Second Payment Towards the Principal

Having extra money at the end of the month is nice but paying off a mortgage faster is just as rewarding. Any net income you currently have (interest – expenses = net income) could be used to make a principal payment towards your mortgage. This second payment would be after the minimum payment has been paid for that month. By making a principal payment, it will lessen the amount of time and money needed to completely pay off the mortgage.

Making a principal payment of $250 per month will save $44,056 in interest and shorten the term of the loan to 14 years and 9 months. This cut the length of the mortgage in half and saving a lot of money in the process.

Ensure your bank is aware that this extra payment is for the principal only.

3. HELOC Banking Strategy

The velocity banking mortgage repayment strategy is a bit complex, but very effective. As you’ve had your mortgage for a few years, and currently owe less than what it’s valued at, banks will allow you to open a Home Equity Line of Credit (HELOC). This HELOC will act as your checking account, receiving direct deposits from your income streams, have an individual debit card, and act just as a normal account would.

The key here is to make lump sum principal payments to your mortgage with the HELOC balance, and then paying off the HELOC with your positive net income. Then each and every time the HELOC is fully paid off, you continue making lumpsum payments until the mortgage has been paid off.

Using a HELOC, this mortgage could be paid off in as little as 6 years and 5 months, paying only $15,582 in interest payments.

The HELOC will allow you to free up some capital for unexpected expenses, unlike a traditional mortgage repayment strategy. The strategy also requires that you have available net income at the end of every month. 

4. Downsize Expenses to Maximize Repayment

If you’re one of the millions of people living paycheck to paycheck, you may want to take a look at your expenses. Driving a new car can feel great, but your wallet is probably hurting, and your long-term debt obligations are questioning their existence. Downsizing on your spending habits will ensure that extra money could be used to pay off your mortgage faster.

Taking a long-term view at life instead of living in the short-term can open up a wide range of opportunities for reducing the amount of debt we have. Mortgages tend to be our biggest personal debts and should be paid off as soon as possible.

Creating a budget is one of the most useful tools that we can use to organize our income and expenses. By setting our primary goal of paying off our mortgage quickly, we can then approach a budget with the right mindset and decision-making process to ensure we can afford more than monthly payments. Learn more about how to create a budget.

5. Refinance Your Mortgage

A 30-year fixed-rate mortgage tend to have higher interest rates than those with a 15-year term. This is because the bank has to lend out money for an extended period of time, increasing the risk for default. Refinancing a mortgage to a shorter timeframe will reduce some interest expenses but will ultimately increase the monthly minimum payment.

Ensure the new mortgage has a lower interest rate than the previous mortgage.

If not, you’re wasting money.

When refinancing, it’s best to look over your current budget and determine how much money can go towards the mortgage every month. This is a permanent decision and could potentially leave you owing more than you can afford.

Refinancing the mortgage within the example could mean that the interest rate could drop from 4.5% to 3.5%. The fixed-rate would then be 15 years instead of 30. The refinancing would save $53,726 in interest expenses.

See mortgage refinance rates where you live here.

6. Make a Large Down Payment

The strategy is simple, put down as much as you can to lessen the amount of money owed within the mortgage. The more money you can put down initially, the less amount of interest, fees, and expenses you’ll incur throughout the life of the loan.

A typical down payment for a house is between 3 and 10 percent. Aiming for 15-20 percent may seem like a big difference, but it makes a huge difference in the amount of money being paid in interest.

Example: 30-year fixed-rate, 4.5% APR:

  1. $100,000 house purchased with 3% down:

Mortgage of $97,000 +

Down Payment of $3,000 +

Interest payments of $85,040

Total Paid: = $185,040

  1. $100,000 house purchased with 15% down:

Mortgage of $85,000 +

Down Payment of $15,000 +

Interest payments of $62,000

Total Paid: = $162,000

As we can see, making a down payment of $12,000 more can save $25,040 in interest payments. Coupled with another strategy such as making a second payment towards the interest, the amount of time to pay off A will take significantly longer than B.
How Low Will Mortgage Rates Go?

Mortgage rates continue to drop for the sixth straight week. How much lower can they go?

For the last several weeks, it seems as though the mortgage rates are playing a game of limbo...and winning. Every time you look at the most current mortgage rates for fixed rate loans, they have dropped below the historic lows that they were already at.

According to Freddie Mac, one of the leading companies that tracks mortgage rates, you can get a mortgage loan for 4.54 percent right now if you qualify. That means that if you have great credit, a good income and at least 20 percent to put down on your home, you may be able to get this historically low rate on a 30-year fixed rate mortgage. That rate is down about 0.02 percent from last week’s ending rate and down from the 5.25 percent rate that they were at one year ago.

If you are looking for an even lower rate, a 15-year fixed mortgage is at 4 percent for qualified buyers. That’s a 0.03 percent drop from last week’s rates and it’s a 0.69 percent drop from the rates from one year ago.

While these rates are super low, these aren’t the lowest rates you can get. If you shop around and you are a qualified home buyer, you may be able to find rates even lower than those if you are willing to check with various mortgage lenders before making your purchase. However, because of the recent mortgage problems we’ve had in the United States, lenders are being much more careful about who they loan money to. Freddie Mac and Fannie Mae have tightened the restrictions surrounding the types of loans they will purchase and guarantee. This means that mortgage lenders have to tighten their standards as well.

This means that you may not be able to qualify for these low rates even if you have had a mortgage for years and you are looking to refinance. Self-employed homeowners wishing to refinance so they can make home improvements are getting turned down for the best rates even though they have a good track record of payments. Many lenders are not offering premium loans and rates to the self-employed because they pose a higher risk than the homeowners and home buyers who have traditional jobs.

So as rates continue to drop, the question must be asked: How low are they really going to go? There was a time just a couple months ago when we thought mortgage rates wouldn’t go back down for a while. Now they are at their lowest levels yet and they have dropped for six straight weeks. How much lower do you think they can get?

Five Things to Look for in a New Neighborhood

Choosing the ideal house for you and your family is one part of the searching process, but you also have to make sure you move into the right neighborhood.

Taking advantage of today’s mortgage rates and buying a home is a great thing to do if you can qualify. With the idea of buying a home, though, comes the idea of searching for the ideal neighborhood. Of course, you won’t know all the nuances and other tidbits of information of your neighborhood until you have lived there for a while. But you can still look for some red flags and other signs that may tell you if it’s not the ideal fit for you or not.

1. Look at the businesses around your new home. This will be a great indicator to tell if this is the type of neighborhood that you want to live in. For instance, are there several tattoo parlors, payday loan shops and businesses like that? If so, you may want to look for a different neighborhood if you are a family with children. Of course, that’s not to say that these businesses or the people who frequent them are dangerous, but it is worth noticing to determine if you want to surround yourself with these types of establishments before making your final decision on a house.

2. Notice the number of vacant businesses. A couple vacant businesses in and around the neighborhood is not necessarily a bad sign, but if there are several, it could be a sign that the neighborhood is in the decline. If you plan on staying in the neighborhood for a long time, make sure you take this into account before making your final decision.

3. Look for the police. If you see police in the area often, it could be a sign that a strong police presence is needed in the neighborhood. While seeing the police cars patrol your streets may give you a sense of security, it is also a sign that there are many problems in the area that require police involvement.

4. Take note of the streets. How quickly do the streets in the neighborhood get cleaned off during the winter months? Does the city make a habit of planting new trees and shrubs along the median or the sides of the street? Are the streets clean or piled with uncollected trash? Keep all of these questions in mind when evaluating your new neighborhood.

5. Are there neighborhood activities to participate in? Many neighborhoods have block parties, yard sales and other activities that all the residents can enjoy during the warmer months. When you take a drive through the neighborhood, do you see children playing in the yards and residents working in their flower beds? These are just a couple signs that this could be the neighborhood that is best for you and your family.

Are You Afraid of Buying a House Right Now?

Many potential home buyers are hesitant about buying a home in this economic climate. Are their hesitations unfounded?

Buying a house these days should be something that many potential buyers would jump into. Low mortgage rates, low prices and lots of choices are like the perfect situation for buyers. So why aren’t they chomping at the bit to buy homes?

Many house hunters are becoming paralyzed by the fear of buying a house. Although it is the dream of most Americans to be a homeowner, the uncertainty of the financial market makes it difficult to be comfortable with such a large purchase and commitment. Others think there is still room in the market for prices to drop even further so they want to wait until that happens so they can save even more money on their purchase.

According to Lawrence Yun, the chief economist for the National Association of Realtors, this type of behavior among potential home buyers is not out of the ordinary. In fact, it’s rather normal. He said that it is similar to when the stock market crashes. Investors want to wait and see what’s going to happen before they jump into any more stocks.

Reports say that home sales figures have dropped by about 25 percent when compared to last year’s sales. That means that there are more people simply waiting to see what’s going to happen before they jump into the real estate market. Real estate agents are finding other jobs to supplement their income because they simply are not making money from home sales these days.

Part of the reason for the drastic drop in home sales is because many people who already own a home and want to move to another one are having problems selling their current home. Until they can sell their existing home, it is almost impossible to move to another one. Unfortunately, with the way the market is, homeowners have to drop the sale price of their home to a level that is below what they may have paid for it. As such, they are losing money. Some buyers have even resorted to moving in with family or renting a small apartment for a while so they can save up money for a down payment on a home.

If fear has gotten a hold of you and forced you to put your dreams of owning a home on hold, there’s nothing wrong with taking a little risk. Take some time to do some research and you can find a really good deal these days. You may never be able to get a bargain like this again!

First Time Homebuyers with Good Credit Will Benefit from Housing Problems

If you've been renting, waiting for the housing market to collapse, the last week is good news for you. Houses are about to get a whole lot more affordable.

Declining home prices hurt those of use who own. Our equity is slowly deflating. But for many people who decided to wait to purchase a home, the last week has put in play additional forces which will lower home prices.

On Monday, the Fed signed off on new mortgage regulations that make it tougher to get a loan. The new rules force lenders to document income, and also require lenders to ensure that homebuyers can afford the purchase once insurance and taxes are calculated into the payment. They are good rules but they will push many out of the housing market or lower what buyers can afford.

On the same day, the Wall Street Journal reported that mortgage insurance is becoming much tougher to get. The paper stated that:

"While it's difficult to guage the severity of the impact, industry executives concede that insurers' tigher standards are affecting the market." Michelle Collins, an executive at Shorebank, Corp. a community-development bank in Chicago said that "easily 70% of the previous set of borrowers will not be able to buy."

For those of you unfamiliar with mortgage insurance, it's often required by the mortgage lender if a buyer has less than 20% to put down on a house. It protecets the lender from a buyer who has little equity in their homes. Over the last couple of years, buyers got around mortgage insurance using 80-20 mortgages. The buyer would use a mortgage to finance the first 80% of the home and then use a second mortage or home equity loan to finace the remaining 20%. That practice has been wiped out, leaving buyers who don't have a downpayment with mortgange insurance as the only alternative. Now, for many even that option is closed.

Banking trouble will also depress home prices. With banks facing steep losses and having trouble with their balance sheets, they will reduce lending to all but the most credit worthy.

All of this means that there will be fewer people and fewer dollars in the market. Supply and demand tells us that if demand drops, so must price. And prices have fallen. The National Association of Realtors says that:

"The aggregate median existing-home price is projected to fall 6.2 percent this year to $205,300, and then rise by 4.3 percent in 2009 to $214,100."

This quote came out on July 8, a week before the current embroglio. I think based on recent events, their 2009 calculation is wishful thinking. I bet the fall in 2008 will be steeper than 6.2% and prices will continue to decline in 2009 and possibly into 2010. Prices will have to fall another 20% to get them back to 2001 levels, when things started to get crazy. The stock prices of major banks are falling back to 2001 levels so I think it's possible that housing could follow a similar trajectory.

All of this is somewhat depressing for a homeowner, of which I am one. But it's great news for first time buyers with good credit. If only I could have stayed in my apartment a few years longer.

Average 30-Year Mortgage Rate Rises Above 5%

Freddie Mac today released the results of its Primary Mortgage Market Survey® (PMMS®) in which the 30-year fixed-rate mortgage (FRM) averaged 5.00 percent with an average 0.7 point for the week ending October 22, 2009, up from last week when it averaged 4.92 percent. Last year at this time, the 30-year FRM averaged 6.04 percent. So mortgage interest rates are almost 100 basis points below what they were last year.

Freddie Mac today released the results of its Primary Mortgage Market Survey® (PMMS®) in which the 30-year fixed-rate mortgage (FRM) averaged 5.00 percent with an average 0.7 point for the week ending October 22, 2009, up from last week when it averaged 4.92 percent. Last year at this time, the 30-year FRM averaged 6.04 percent. So mortgage interest rates are almost 100 basis points below what they were last year.

Shopping around though, you can still find a 30-year mortgage under 5% if you hasve good credit. The best 30 year mortgage rate in Massachusetts (where I live) according to the BestCashCow mortage rate tables has an APY of 4.980% with fees of $1,135.

The 15-year FRM this week averaged 4.43 percent with an average 0.6 point, up from last week when it averaged 4.37 percent. A year ago at this time, the 15-year FRM averaged 5.72 percent.

The five-year Treasury-indexed hybrid adjustable-rate mortgage (ARM) averaged 4.40 percent this week, with an average 0.6 point, up from last week when it averaged 4.38 percent. A year ago, the 5-year ARM averaged 6.06 percent.

The one-year Treasury-indexed ARM averaged 4.54 percent this week with an average 0.6 point, down from last week when it averaged 4.60 percent. At this time last year, the 1-year ARM averaged 5.23 percent.

(Average commitment rates should be reported along with average fees and points to reflect the total cost of obtaining the mortgage.)

"Following bond yields, long-term mortgages rates edged up slightly this week," said Frank Nothaft, Freddie Mac vice president and chief economist. "Although rates for 5/1 ARMs and traditional 1-year ARMs are around half a percentage point below 30-year fixed mortgages, consumers appear to be seeking the stability of fixed-rate mortgages. According to the Mortgage Bankers Association, ARMs averaged only about 6 percent of the number of mortgage applications in September and October thus far.

"The housing market is still trying to recover in the second half of the year. The Federal Reserve reported in its October 21st regional economic review that housing market conditions improved in recent weeks, primarily from a pickup in sales of low-to medium-priced houses. However, residential construction activity was reported to remain weak in most areas. New construction of single family homes rebounded in September, rising at a 3.9 percent annual rate, but did not erase all of the declines set in August, based on figures released by the Department of Commerce. Moreover, homebuilder confidence, as measured by the National Association of Homebuilder's Housing Market Index, fell slightly in October and marked the first decline since January of this year."