Certain rates on this table are from BestCashCow.com advertisers.
Compensation may impact the order in which rates appear.
This is to inform our readers that BestCashCow has received compensation for the placement of this bank offer.
Savings Account National Average Rate: 0.23% ?
What are the Best Bank Accounts with High Interest Rates?
As of November 6, 2026, the top online savings rate is 5.00% APY from Axos Bank, followed by 4.40% APY from PiBank, a division of Intercredit Bank, NA and 4.35% APY from Vault Bank. In the table below, you will find a list of the highest online savings account rates, ranked in
descending order by interest rate currently offered. Online bank accounts are slightly different in terms
of their features and the services offered. Please also refer to the section below
entitled “Best Online Savings Account Rates".
Axos One Savings. Requires maintaining $1,500 in checking account earning 0.51% and $1,500 per month in direct deposits (or maintaining $5,000 in checking if no direct deposit).
Last change:
↑0.79% on October 12.
Rate History: 4.21% → 4.21% → 5.00% → 4.21% → 5.00%
Jeff Talmage | Aug 22, 2025
Echoing the other negative reviews here. Avoid because rate is bait-and-switch, website is awful and service is not acceptable (provided by offshore reps who barely speak English, raise their voice and ad...
Read More
Last change:
↑0.15% on October 21.
Rate History: 4.60% → 4.40% → 4.10% → 4.25% → 4.40%
rudy cecchini-1757884975 | Sep 14, 2025
These people SUCK!!!!! After days of jumping through hoops proving I am a citizen; have a valid driver's license; pay my bills on time; etc. they declined my application and would NOT give a reason. I got...
Read More
Online Savings Account. Account is indicated as not currently available to new customers, but bank accepts new customers who sign up to be notified after 1-2 weeks.
Last change:
↑0.15% on September 25.
Rate History: 4.20% → 4.20% → 4.20% → 4.10% → 4.25%
louise k | Feb 16, 2026
Put my name on the waiting list and got contacted 72 hours later. Opened account and now I am getting 4.20%.
Last change:
↑0.30% on October 2.
Rate History: 4.40% → 4.30% → 4.05% → 3.90% → 4.20%
smithy1968 | Mar 20, 2025
A non-customer-friendly organization that just switches between two contaminated brands trying to bring back some sort of goodwill that it had before it started selling fake foreign currency CDs in 2006 an...
Read More
LevelUp Savings Account. Requires direct deposit of at least $250/month. Bank's standard online savings rate is 3.30% APY.
Last change:
↑0.20% on September 25.
Rate History: 3.82% → 4.00% → 3.82% → 4.00% → 4.20%
jaydub | Aug 18, 2025
Sophomoric as hell. I opened a LevelUp account for the 4.40% rate (now 4.20%). Rate requires automatic $250 deposit each month which I made, but I now realized that I never got that rate. Customer servic...
Last change:
↑0.16% on October 1.
Rate History: 4.47% → 4.41% → 4.26% → 4.01% → 4.17%
79Thru | Mar 21, 2023
Parent seems to be owned by a large Chilean bank. Not saying this is good or bad, but it is complication, especially in the current environment.
Read More
Growth Savings rate for new customers. The rate for existing customers is 3.85% APY.
John N. Maclean | Jul 5, 2024
I took out a substantial CD with Forbright, a small bank that tries hard. At the time, it was the highest rate around. The bank officer I dealt with most, Walid, knocked himself out to be helpful and get t...
Last change:
↑0.10% on October 7.
Rate History: 4.00% → 3.90% → 4.10%
bws/esc | Apr 27, 2023
have had 3 cd accounts. all interactions with instructions for disposition of funds were never exactly enacted as discussed and requests for confirmatory emails never sent with details as terms discussed. ...
Read More
High-Yield Savings Account. Outbound transfers limited to $10,000/day or less.
Last change:
↑0.05% on October 12.
Rate History: 4.00% → 4.00% → 4.00% → 3.95% → 4.05%
m abram | Jun 22, 2025
I have had multiple CD's with this bank and have never had a problem. Easy account setup. Interest on CD's is transferred on time to my external checking account every month. You can call by phone or leave...
Read More
Last change:
↑0.06% on September 22.
Rate History: 4.01% → 4.00% → 3.99% → 3.95% → 4.01%
2 Months with Vio Bank | Sep 4, 2025
And I discovered that they play bait and switch and have no problems lying. This system won't let me give it zero or negative stars so I have given it one, but that is at least one too many.
Read More
UFB High Yield Savings. Bank reports that this rate is for new customers only.
Last change:
↑0.75% on November 2.
Rate History: 3.26% → 3.26% → 3.26% → 3.26% → 4.01%
Miles Jacobsen | Jul 18, 2023
I got into this one back in early April for the rate. It was the first to hit 5%. I put up with all sorts of annoying thing getting the account funded (including a 5-day wait period during which they had...
Read More
High Yield Money Market Account. Only available to residents of Arizona, Minnesota and North Dakota.
Last change:
↑0.25% on July 29.
Rate History: 4.50% → 4.15% → 4.00% → 3.75% → 4.00%
Jean-Marc | Nov 10, 2023
Just found out after submitting all my personal information:
"Western also allows one free outgoing wire per month."
"External transfers from Western State Bank Online Banking: After 60 days you will h...
Last change:
↑0.15% on October 21.
Rate History: 3.90% → 3.85% → 3.75% → 3.85% → 4.00%
HAL1975 | Aug 2, 2023
Sallie mae is just a horrible institution. We've done business with them before and swore on the holy bible not to go near there again, but a 18 mos cd at 5.55% brought us back.
I've been with this bank for 6 months and have not had any problems. Bill pay works good. The 24 month investing CD is another vechile I use. Rates are above average considering the national rate. I'd reco...
Read More
Surge Money Market. Bank reports that this rate is available for new accounts only. External transfers are limited to $5,000/day and are not free.
Last change:
↓0.10% on December 22, 2025.
Rate History: 4.40% → 4.35% → 4.22% → 4.10% → 4.00%
Jason T | May 30, 2023
They really do pay this amount, but the account lacks any functionality and they are constantly looking for some sort of add-on fee to enable them to claw back the interest. Any bank with a higher rate an...
Read More
Online transfers limited to $1,500 per day and $10,000 per month.
AEM | Sep 18, 2023
I agree with another user, this bank is very poorly put together, and may very well be an operation in large part used to extract and sell people's personal information. I called customer service and had ...
Read More
Last change:
↑0.34% on September 18.
Rate History: 4.26% → 4.15% → 3.80% → 3.61% → 3.95%
Yat 1965 | Mar 19, 2022
Problem with ties to puppy mills. I closed a cct. https://www.americanbanker.com/news/tab-bank-dragged-into-seedy-world-of-puppy-mill-loans-by-fintech-partner
Last change:
↑0.15% on September 25.
Rate History: 4.15% → 4.05% → 3.90% → 3.75% → 3.90%
JBaker65 | May 6, 2023
Fully functional bank account that would be great for my needs, but the quarterly interest payment thing is a real nuisance. I wish they would change it. It isn't market.
Last change:
↑0.15% on September 25.
Rate History: 4.15% → 4.05% → 3.90% → 3.75% → 3.90%
TJ Boone | Jun 2, 2026
Opened an account with Bask several years ago for all of American Airlines miles when rates were close to zero. At some point I switched to an interest bearing account and then at some point I moved to an...
Read More
Direct Savings. Bank reports that this rate is available for new accounts only.
Last change:
↓0.10% on December 15, 2025.
Rate History: 4.05% → 4.10% → 4.05% → 4.00% → 3.90%
Neil | Dec 18, 2023
I submitted a CD application 18 months 5.50 APY over a week ago and my application was declined no reason was given, I have the funds in another bank for transfer, credit score over 800. I think the reason...
Read More
Last change:
↑0.05% on July 20.
Rate History: 4.25% → 4.15% → 4.05% → 3.85% → 3.90%
jp2 | Jul 1, 2022
not really an onllne bank. compare this interface that gives you no information with that of any other bank (I cannot even confirm the rate). cannot switch in and out of cds or np cds. just not an online b...
Read More
STAY AWAY !
They closed my accounts with no warning.
After multiple successful direct deposits and mobile checks deposits, they claimed one of the three checks I deposited a few days ago was fake. No...
External transfers may take up to 3 business days and may be limited to $25,000/day.
Last change:
↑0.20% on October 27.
Rate History: 3.50% → 3.40% → 3.30% → 3.55% → 3.75%
mcriss | Oct 23, 2023
Synchrony Bank recently closed 3 of my accounts with them and this decision was completely unwarranted. I had two Guitar Center cards and one Levin Furniture card. I found out about this through a push not...
Read More
Bank is offering a boosted rate of 4.25% for 8 months for new customers.
Last change:
↓0.50% on September 26.
Rate History: 3.50% → 3.50% → 4.00% → 4.25% → 3.75%
FROZE-ACCOUNT | Jan 10, 2024
Account was frozen (over 400K) after they confused our account with another account / person whose name was not even very similar. We were treated like dirt after 12 years and "Guilty until Innocent". I ha...
Read More
Platinum Savings. Bank reports that this rate is available for new accounts only.
Last change:
↓0.10% on November 25, 2025.
Rate History: 4.30% → 4.10% → 4.00% → 3.85% → 3.75%
MrBond | Feb 25, 2023
I have been working for this company more than 5 years. I would not recommend any investment with First Citizens Bank. They are the worst performer on the market based on the customer and employee reviews...
Read More
We would not be having all this trouble with people sealing money out of other people's bank accounts if we were to just stop using fancy banking like onlinebanki
Bank reports that this rate is for new customers only. Bank also charges ACH transfer fees and routinely lowers rates for existing customers below those advertised.
Last change:
↑0.15% on September 30.
Rate History: 3.81% → 3.71% → 3.61% → 3.51% → 3.66%
LarryMass | Dec 8, 2020
Everyone here in Boston raves about Salem Five but it is shithole operation filled with nasty entitled people. As for this online savings product, the fees are ridiculous, the transfer charges are obnoxiou...
Read More
Last change:
↓0.10% on March 23.
Rate History: 4.15% → 4.05% → 3.85% → 3.75% → 3.65%
BW | Jul 17, 2021
I've been with this bank for 6 months and have not had any problems. Bill pay works good. The 24 month investing CD is another vechile I use. Rates are above average considering the national rate. I'd reco...
Read More
Last change:
↓0.10% on July 2.
Rate History: 4.10% → 4.00% → 3.85% → 3.75% → 3.65%
LenaL | May 2, 2022
Barclays is the worst. Transfer speeds even worse than Synchrony now. Service is worse than anything. Save yourself the trouble of getting sucked into rates that are sometimes competitive and choose anythi...
Last change:
↑0.10% on September 18.
Rate History: 3.70% → 3.65% → 3.55% → 3.50% → 3.60%
HAL1975 | Aug 2, 2023
Sallie mae is just a horrible institution. We've done business with them before and swore on the holy bible not to go near there again, but a 18 mos cd at 5.55% brought us back.
Last change:
↓0.10% on December 22, 2025.
Rate History: 4.20% → 4.00% → 3.90% → 3.65% → 3.55%
NRB | Mar 14, 2018
Poor service. Condescending attitude.
Savings application denied without giving reason (Equifax file had a freeze because of hacking history) and not advising customer of need to unfreeze credit file for a...
Read More
Money Market Premier. Bank reports that this rate is for new customers only.
Last change:
↓0.25% on March 31.
Rate History: 3.50% → 3.40% → 4.00% → 3.75% → 3.50%
Mike Brown | Jul 6, 2023
This is an example of a bad bank. Their online process for purchasing a CD is horrible. You fill it out and it rejects it after all of your private information is disclosed. They there customer service is ...
Read More
Rate requires download of bank app and recording of over 12,500 average daily steps (or 10,000 if over age of 65). Customers maintaining $5,000 in a checking account may qualify for 4.50% rate.
Last change:
↓0.25% on September 11.
Rate History: 4.45% → 4.20% → 4.00% → 3.75% → 3.50%
JGothelf | Oct 11, 2022
Glad to have found this one and thanks to bestcashcow for not hiding the best rates like bankrate does
Read More
Last change:
↓0.25% on November 2.
Rate History: 3.75% → 3.75% → 3.75% → 3.75% → 3.50%
Azoic | Feb 25, 2022
I joined Citi with a Costco-VISA card. An Accelerate followed, and then a checking account.
Costco-VISA is necessary for using a credit card at Costco, otherwise cash is necessary.
Accelerate Savings w...
Read More
I have 5 other cd's at competing banks and have not had trouble. I tried 3 times today to open one w/ bradesco and it repeatedly declines my app after I input the code they sent me. Customer service was no...
Read More
Cornerstone Money Market Account. Bank reports that this account is available to new customers only. Old account holders in the savings product are earning 1.10%.
Last change:
↓0.05% on September 11.
Rate History: 3.60% → 3.55% → 3.50% → 3.45% → 3.40%
2 Months with Vio Bank | Sep 4, 2025
And I discovered that they play bait and switch and have no problems lying. This system won't let me give it zero or negative stars so I have given it one, but that is at least one too many.
Read More
Last change:
↓0.40% on December 22, 2025.
Rate History: 4.85% → 4.25% → 4.00% → 3.75% → 3.35%
J Dally | Jun 13, 2023
I'll steer clear of Dollar Savings Direct and My Savings Direct until they guarantee users at both online divisions their best rates. Banks have the right to segment their customers yes, but these games w...
Read More
We would not be having all this trouble with people sealing money out of other people's bank accounts if we were to just stop using fancy banking like onlinebanki
Last change:
↓0.40% on December 22, 2025.
Rate History: 4.35% → 4.10% → 3.75% → 3.35%
not perfect but | Apr 25, 2023
with all of these online bank, including the well known ones, delaying transfers forever in order to fund these high rates, this one still executes inbound and outbound transfers immediately.
Read More
360 Performance Savings Account. Rate available for new account holders only.
Last change:
↑0.10% on October 21.
Rate History: 3.20% → 3.10% → 3.00% → 3.10% → 3.20%
Robert B | May 19, 2026
I have read these reviews and noticed how old they are. My experience with Capital One has been very good. I have had CDs and savings accounts. All of my transactions have been on line. I have enjoyed usin...
Read More
Last change:
↑0.10% on October 15.
Rate History: 3.20% → 3.10% → 3.00% → 3.10% → 3.20%
Dev1ldog | Nov 8, 2023
I see nothing exciting about AmEx Bank. Sign on is a hassle and the rates are adequate. Multiple accounts are not summarized. To cancel maturing CDs require phoning in or snail mail. Above average serv...
Read More
Online Money Market Account. Ally's Online Savings account rate is only 3.75% APY.
Last change:
↑0.10% on October 27.
Rate History: 3.20% → 3.10% → 3.00% → 3.10% → 3.20%
Rad | Aug 13, 2023
Been a customer for a couple of years now with interesting checking, been a happy customer. They give you a $10 reimbursement on atm fees per statement cycle. They pay you to leave your money there curre...
Read More
Last change:
↑0.10% on November 4.
Rate History: 3.20% → 3.20% → 3.00% → 3.10% → 3.20%
AVOID_ READ_CAREFULLY | Jan 10, 2024
AVOID at all costs. We read the addendum to the final page of the LENGTHY account agreement mailed to us after completing the online portion. Guess what? It gives this sweet seeming Discover Bank access to...
Read More
Last change:
↓0.15% on June 3.
Rate History: 3.50% → 3.50% → 3.50% → 3.35% → 3.20%
JuanVelasco | Mar 17, 2023
STAY AWAY !
They closed my accounts with no warning.
After multiple successful direct deposits and mobile checks deposits, they claimed one of the three checks I deposited a few days ago was fake. No...
Last change:
↓0.25% on August 31.
Rate History: 4.10% → 3.85% → 3.60% → 3.35% → 3.10%
praveen raj | Jan 18, 2024
Hi,
We've noticed your website is at risk due to spammy comments and contact form submissions, making it susceptible to issues like spammy backlinks and data breaches. Don't worry—there's a simple sol...
Their CD rates are reasonable and their Visa rewards is very good at 2.5% on all purchases up to 10K/month.
Their customer service is polite and helpful.
However, their IT department must need some serio...
Last change:
↑0.25% on October 12.
Rate History: 2.55% → 2.55% → 2.55% → 2.76% → 3.01%
Beenthere | Jan 29, 2024
Tried to enter information on line to open a 5 year CD, multiple time and wasn't accepted. Talked to a live person who was of no help at all. My credit score is over 800 and I have plenty of money in oth...
Read More
Last change:
↓0.15% on June 12.
Rate History: 3.60% → 3.50% → 3.25% → 3.15% → 3.00%
Jenny Kingston | Jun 10, 2024
I guess customer service is in the US (not sure). I'd rather that someone in the Philippines answered though. These people are so poorly trained and ill informed that I do not trust them with my personal...
Read More
Last change:
↓0.25% on October 6, 2025.
Rate History: 3.90% → 3.60% → 3.35% → 3.25% → 3.00%
NRB | Mar 14, 2018
Poor service. Condescending attitude.
Savings application denied without giving reason (Equifax file had a freeze because of hacking history) and not advising customer of need to unfreeze credit file for a...
Read More
Last change:
↑2.95% on September 11.
Rate History: 0.01% → 0.05% → 3.00%
Last change:
↑2.95% on September 11.
Rate History: 0.01% → 0.05% → 3.00%
RYAN S | Nov 28, 2022
While USAA was at one point a great option for all your banking needs, the service has deteriorated so much that I'm currently in the process of changing banks after more than 2 decades. The final straw w...
Read More
bad bank hold your deposit over months without credit in your account, no interest, they don’t want pay you interest , they want your money with 0% interest.
Read More
Last change:
↓0.10% on November 14, 2025.
Rate History: 2.90% → 2.80% → 2.70%
Rob | Dec 25, 2023
I joined in PENFED in Spring Of 2023 after 15 yrs of belonging to one of the banking giants. I found my accounts dwindling fast unexplained decreases. I decided to close the account but had to return a mer...
Last change:
↓0.40% on September 7.
Rate History: 3.00% → 2.75% → 1.00% → 2.75% → 2.35%
JohnC | Oct 11, 2020
You probably thought - as did I - that you were looking at a site that belongs to and was the responsibility of Gateway First. After all it includes their headings, selected financial statements, many pag...
Read More
Last change:
↑0.20% on September 25.
Rate History: 2.15% → 2.05% → 1.95% → 2.15%
Amanda Frank | Feb 25, 2023
HORRIBLE SERVICE. My son's campus checking account was hacked and over $9000 was stolen. Fraud department was impossible to reach and we waited on phone several days for over 2 hours at a time. They too...
Synchrony Bank recently closed 3 of my accounts with them and this decision was completely unwarranted. I had two Guitar Center cards and one Levin Furniture card. I found out about this through a push not...
Read More
All rates listed are Annual Percentage Yield (APY).
The APY rate in a savings account or money market account is a variable rate that is subject to
change at any point. The Min listed is the minimum deposit account balance required to obtain the rate listed.
Frequently Asked Questions About Online Savings Accounts
What does APY mean?
“APY” stands for annual percentage yield. Savings rates are displayed in terms of APY to indicate the effective annual-interest return, including the compounding of interest, over the course of a single year. $100,000 deposited in a savings or CD account with a 1.20% APY will earn $1,200 in the course of the year, but monthly interest in the first few months may be less than $100 a month (this also depends on the number of days in the month). Hence, the APY rate is ordinarily a couple of basis points above the real interest rates. Unlike with a CD, your actual APY in a savings account or money market account may vary if the rate changes.
What is a savings account?
A savings account is one of the simplest types of bank accounts. It allows you to store cash securely and earn
interest on your money.
What is a money market account?
The differences between a savings account and a money market account are largely arcane. Some savings accounts are limited by US federal regulations to six outbound
transfers per month (the bank may allow additional access for a fee). Money market accounts are technically not bound by those limitations and offer more ways to access deposits by issuing checks and debit cards. Prudent consumers will compare the two interchangeably, focusing primarily on rates and service among FDIC-insured
banks (or NCUA-insured, for credit unions). Consumers who maximize their use of online savings and money market accounts access these accounts through ACH transfers
that are easily set up on the online bank’s website so the additional ways to access deposits that money market accounts offer are rarely valuable.
How Do Online Savings And Money Market Accounts Work?
Over the last two decades, online banks have emerged to offer depositors higher rates on their online savings and money
market accounts than are available in the major money center banks and in smaller brick-and-mortar banks.
Since these online banks do not have expensive branch networks to maintain, they usually pass some of their
savings back to depositors in the form of higher rates.
All online banks and local banks listed on BestCashCow are FDIC Insured.
Unlike certificates of deposit (CDs) or time deposits, money in savings and money market accounts accrue interest on a daily rate. The best yielding savings rates can conceivably change from day-to-day with new online banks emerging or existing banks more aggressively seeking to raise the capital accounts. It is important to check back on BestCashCow regularly to be sure that your savings accounts continue to earn the most competitive rates, no matter what the rate environment is.
The table above lists the highest yielding online savings account rates.
How Do I Open An Online Savings or Money Market Account?
The process of opening an online savings account or money market account is usually very simple. Banks ordinary ask you a few questions to verify your identify.
These questions include seeking information from a state or government issued ID, such as a driver’s license. Due to increased US anti-money laundering rules and
Department of Homeland Security requirements, it is very likely that you will also be asked to produce a photocopy of your license and a picture taken from your
iPhone or other smartphone and emailed to the bank will ordinarily suffice.
The bank may ask for information regarding a correspondent account from which you
intend to have them draw the money to provide the initial funding. You therefore will need the ABA number and account number from an existing account that you have.
They will verify this account by having you log back in to confirm the amounts of one or two small deposits to your correspondent account before they draw the funds
from this account. Finally, many banks do a “soft” credit pull from Experian, Equifax or some other credit rating agency. While your credit rating will ordinarily
not be affected, the application process may involve your answering questions about where you have lived, loans you may have had, past employers or cars you may have
owned. Many people do not enjoy providing the amount of personal information required over the internet; therefore, some of the larger online banks have 24-7 customer
service to guide you through the process. You can see the experiences of others with a given online savings bank that you are considering by reviewing the comments
left in BestCashCow’s table above.
Are online savings rates always better than rates at brick-and-mortar banks?
No. Online banks often offer higher savings and CD rates because they have lower expenses by not having to maintain brick-and-mortar locations.
You should also check rates at local banks and credit unions. Unlike other websites, BestCashCow.com compiles all of these rates, listing them in an unbiased manner
that shows the proximity of each bank or credit union to you. Please access these rates using the tabs above.
Depending on where you live, there may be banks and credit unions offering rates still higher than the
best online savings rates.BestCashCow maintains the largest
rate database – including rates on over 2,000,000 bank products
from all 8,000 banks and 7,700 credit unions in the US –
in enable you to compare online rates with local rates in
your area.
Are Online Savings accounts safe?
All bank accounts listed on BestCashCow are insured by the Federal Deposit Insurance Corporation ("FDIC").
The FDIC is a federal government chartered institution that provides insurance to a maximum amount of $250,000 per individual per institution (or $500,000 for joint account holders). All deposits (CDs, Checking, Savings Accounts) held in the same type of ownership at a single financial institution are only insured to $250,000.
However, funds held in different types of ownership (Individual, Joint, Trust, Retirement) may fall under separate FDIC insurance provisions.
BestCashCow.com strongly recommends that you deposit savings in only FDIC insured institutions and that you do not exceed FDIC coverage limits.
Please visit the FDIC's website to determine your coverage limits based on your circumstances.
What are the advantages of Online Savings accounts?
Higher interest rate.
Often top notch online functionality with 24/7 access, 365 days a year. You can check your balance, update your contact info, make transfers, and order deposit slips at any time. For more pressing issues, customer support is also usually accessible 24/7, so you can talk to an actual human instead of your computer screen.
Superior online and mobile access. Many traditional banks have been slow to adopt the best web and mobile features to improve the customer experience online.
Easy money transfer capabilities to and from a primary checking account.
Liquidity. Depositors can withdraw their money at any time.
What are the disadvantages of Online Only banks?
A variable interest rate. While most leading online banks have not lowered rates significantly in past years, any savings rate can conceivably be lowered at any time.
There are often new entrants to the market that can disappear as quickly as they arrive on the scene.
Interaction is only via phone or Internet. You cannot walk into a branch and talk to a
customer service representative if you have a problem with your savings account. Nonetheless,
the leading, high profile online banks provide virtually instant phone access at all hours to a
representative. However, interaction with some of the smaller online banks can be more difficult
as it is ordinarily limited to business hours in their area of operation.
You cannot get cash or cashier's checks instantly as you can in a branch bank, and matters
where you need to rely on the US Postal system can lead to significant delays and obstacles.
There is no opportunity to build a relationship with a banker should you need a loan or
additional services in the future.
What is the best account for easy access?
Depending on where you live and how accessible the branch is, you may find that the best account for
easy access is through a local bank or credit union. However, today many high
yielding savings and money market accounts provide such easy accessibility, including through mobile apps,
and can enable such easy transfers to a correspondent account at a local bank through ACH transfers, that
more and more people are opening accounts for cash and savings that they do not need immediately.
Is a high-yielding online savings account your best option?
High-interest savings accounts are always an ideal place to keep your emergency fund or any money to which still you need ready access. Your money will be safer than if you stuffed it under your mattress, and it will grow a bit, too.
Investors will find that keeping large amounts of money in savings and CDs provides them with lower returns but cushions them against market crashes like we experienced in 2000 and 2001 and again in 2008 and 2009.
Why do savings rates vary so much?
Even though rates are at levels that are historically very low, there is competition for your money. Like any active marketplace, there are buyers and sellers of
goods and services at different prices.
How do I choose the right savings or money market account?
Begin your search with the table here on BestCashCow.com. In addition to
checking online savings rates, you should also check local bank rates
and local credit union rates.
What is the Best Fixed Rate Savings Account?
BestCashCow strongly encourages people to avoid very short-term promotional rates.
The very nature of a savings or money market account is that the rate can change from
one day to the next. Savings rates may be guaranteed not to change for some very short
length of time, but they are not fixed. If you require a fixed rate or greater certainty
that the rate that you are making will not change, you should consider CDs, which represent
a time deposit, for some or all of your savings.
Recent Performance of Online Savings And Money Market Accounts
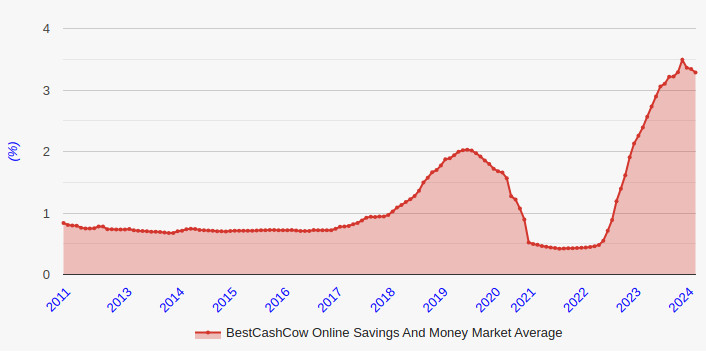
BestCashCow data shows that the highest yielding online savings
account and money market
rates increased from a base around 0.75% through 2017 and 2018 to a peak just over 2.00% in mid-2019.
The Fed Funds rate was lowered in July 2019 and then brought
to zero in early 2020 in response to COVID-19.
As the Federal Reserve raises the Fed Funds rate in 2022
and 2023, online savings rates may eclipse their mid-2019 highs.
The graph below shows how the average rates for online savings and money market accounts have trended over the last several years.
In addition to the broad movement that we see in online savings and
money market account averages according to economic circumstances
and the Fed Funds rate, there is wide variability among rates
offered by the leading online banks.
Even while the online savings average has remained below 0.40% for
most of 2020 and 2021, we have seen some banks offer rates as high
as 0.65% or 0.70% during this time.
Should I consider CDs?
If you are unlikely to require access to your cash for some time, you may also consider certificates of deposit (CDs). While CDs have penalties for early withdrawal
that may even eat into your principal, the rates on 2, 3, 4 and 5 year CDs are ordinarily significantly higher than savings rates. CDs also offer the certainty of
rate stability for the term of the CD. Several sections and articles on BestCashCow can also help you to identify your proper cash allocation between savings and CDs.
With savings rates at such low levels, does earning a higher savings rate or the best savings rate really
mean anything to me?
Even a difference of a couple of basis points (hundredths of a percentage point) can really add up over time, especially on large sums of money.
You may wish to familiarize yourself with the BestCashCow Savings Calculator in order
to understand the importance of compounding interest at higher rates on your savings over time.
If you have not accessed the BestCashCow Savings Calculator or mastered
the magic of compounded earnings, here is the plain and simple truth:
$250,000 deposited at a major money center bank like Chase, Citibank, Bank of America or Wells Fargo is likely earning less than 0.10% APY. That money is
therefore making no more than $250 a year in interest.
That same $250,000 deposited at a leading online bank is earning over 1% or over $2,500.
Even though the increased earnings from high yield savings (in this example, $2,250 annually) is fully taxable at the federal and state and local levels,
wouldn’t you like to be earning that extra income from high-yielding savings accounts?
Are you still hesitant to open a high interest-earning online savings account?
Here are some common reasons people hold off:
You need to make more than six withdrawals a month.
Avoid potential problems by opening a high earning online money market account (some of the best rates available in the table above are actually from online money market accounts), opening a savings account at a bank which does not enforce the 6 transfer limit, tying your account to a correspondent bank’s money market account or checking account at a major money center bank (like Chase, Citibank, Wells Fargo, or Bank of America) where you make one larger transfer each month.
You like having access to a physical branch.
Find out what the minimum balance required to avoid fees on your account at your physical branch,
then transfer the excess balances to a high yielding online savings or money market account.
You’ll continue to have access to the physical interaction and services of the bank with which
you are used to banking, but you will also be dramatically increasing the interest earned on
cash you don’t need over time.
You need to deposit large sums of cash or checks in excess of the online bank’s
mobile deposit limit.
In this case, you need access to a physical branch. See point 2, above.
You want one institution to handle all of your financial matters.
Most online banks do not offer mortgages, credit cards and brokerage services. There is no financial advantage to keeping all of your financial transactions in one or even a handful of institutions.
What is a health savings account?
A health savings account (or HSA) is a tax advantaged medical savings account available to taxpayers
in the United States who are enrolled in a high-deductible health plan (HDHP). The funds contributed
to this kind of account are not subject to federal income tax at the time of deposit.
According to IRS Publication 969 (2016), the interest or other earnings on the assets in the account are tax free and distributions
may be tax free if you pay qualified medical expenses or other expenses not covered by health insurance
such as dental or vision care. Due to the tax advantages of a health savings account, these accounts
should be set up separately through banks offering them (such as Chase or Bank of America) and their
assets should not be comingled with a high yielding online savings account. We know of no online banks
currently offering HSAs.
What is an education savings account?
Education savings accounts, such as Coverdell Education savings accounts and 529 plans, are accounts
that allow family members to obtain certain tax advantages through setting aside funds for a child’s future education.
529 programs are administered at the state level and you must invest in programs
they administer; Coverdell education savings accounts are move flexible (and generally follow
the same rules as IRAs), however we know of no online banks currently offering Coverdell Education
savings accounts.
What is a child savings account?
A child savings account is a savings account in the name of the child with a parent or guardian named
as the custodian on the account until the child reaches the age of 18 or 21 (depending of the child’s state
of residency). A child savings account can be a great way to teach your child the importance of saving money
from a young age.
More information on child savings accounts can be found
here.
Ally and Capital One 360 are among the few online banks offering child savings accounts.
Best Online Savings Account Rates
Finding the best high interest online savings or money market account is a highly subjective exercise.
The best account for your neighbor may not be the best account for you. To help you determine which
account is best for you, we have created the following 7 point checklist:
A competitive interest rate. BestCashCow maintains the most comprehensive list of deposit account rates. The rates above are the best available rates for online savings accounts. In order to ensure that your money continues to grow over time, you may wish to avoid banks which rely heavily on very short term promotional rates (such as EverBank). If you open an account with a promotional rate or even if you open an account where the rate isn’t promotional in nature, you should check back with BestCashCow regularly to be sure that your bank continues to offer one of the most competitive rates.
Full functionality through online and mobile access. Most of the accounts listed above have robust websites and mobile access that enables full functionality. Read the comments from other users before opening an account as they often highlight problems with access.
Assess how the bank provides customer service. Many of the leading online banks now have customer service representatives who are U.S. based and available 24/7 with low wait times. This is often a distinguishing feature that makes a well-recognized bank significantly more attractive than a smaller bank trying to enter the online banking arena.
Absence of fees. Be sure that you are opening an online account with a bank that doesn’t charge fees and has very low minimum balance requirements. American Express, CIT, GS Bank, Barclays and Ally are all well known for low minimum requirements and the absence of any unusual monthly fees.
Easy Access to your Cash through Immediate Online Transfers. The reason why you keep money in savings is for access in an emergency or to take advantage of immediate financial opportunities. You need access to your cash. Yet, some banks impose strict limits on the amount of cash that you can access from your account in a single transfer or limit the numbers of transfers you can conduct over a given time period. Other banks can delay your transfers for days while they make money on the float. You should check with the bank where you are considering opening an online account to understand the restrictions before you open an account. You may also read the comments from other users above as they can highlight which banks enable the best access to your cash.
Stay within FDIC limits! See the section above and read this article.
Use the BestCashCow Savings Calculator to see how important it is to be maximizing your interest on savings accounts over time.
Why You Can Trust BestCashCow
Every year, Americans collectively lose at least $80 billion in income just by putting
their savings in the wrong bank accounts. BestCashCow is the most comprehensive and unbiased
bank rate site on the Internet and our mission is to help you to avoid your share of these
losses. We monitor over 30,000 rates from over 8,000 FDIC-insured banks and 7,700
NCUA-insured credit unions. Take a few minutes to explore the table above to see
the best savings rates currently offered by online banks, or use the tabs to explore
local bank rates or local credit union rates if your prefer to do your banking locally.
By using BestCashCow to move your money to a new bank from one with a low savings rate
you may be able to boost your annual interest earned from savings by more than 10X. Banks
are always competing for your money. Take advantage of it!
In the many years since BestCashCow was founded, we have received a fair number of emails from readers asking various technical questions about how their online savings accounts operate. Perhaps the most common question relates to the difference between a wire transfer and an Automated Clearing House (ACH) transfer.
I have hesitated to write an article on this topic because the issue has become less and less important to those using online banks for their savings and CD products, and ACHs have generally become more transparent and faster. The largest online banks (Goldman Sachs Bank, Purepoint Bank, Ally Bank and others) now process all inbound and outbound transfers instantaneously (and free). As a result, transfer speeds and times have become less burdensome for those banking online and occasionally transferring cash to a separate savings or checking account at a branch where they do most of their daily financial transactions. But, we nonetheless seek to clarify this matter further here.
Wire transfers are a direct bank-to-bank process that technically moves money instantaneously between two financial institutions and can only be initiated by the institution holding the account from which cash is being transferred. Since the process may not be completely automated and a bank employee at the receiving institution may review all transactions before an account is credited for an inbound transfer, it may take several hours to a day for the money to move from one account to another. Otherwise, however, a wire transfer is basically an electronic cashiers’ check - payment received in an account is treated as cleared money and may be withdrawn immediately (and for this reason there is obviously also risk in this process). Likewise, the funds must be available in the outbound account before the payment is issued, and will be immediately debited from the sender’s account as the request is processed. Banks may charge to send or to receive wire transfers, but the fee on either side is ordinarily not greater than $35 for a domestic wire transfer (international transfers may be a little higher).
ACH transfers are similar to a wire transfer, except that they use a clearinghouse and a batch process and may be initiated by the outbound or the inbound account. Since a clearinghouse and a batch process are used, transactions are stored and reviewed and the money may not actually be transferred for a day or even several days (as pointed out above, the largest online banks process these transactions through the clearinghouse immediately, but the smaller ones may take several days – look to the comments in BestCashCow’s tables to see what types of speeds users experience). Even if the money is received immediately, the recipient bank may not allow the account holder to withdraw the money right away, especially when the transfer is initiated through that bank’s interface, as they need to protect themselves from fraud liability laws that ordinarily apply to ACH transfers. When initiating an ACH transfer from an incoming account at an online bank, there is a risk of overdrawing from the account from which you are pulling cash (and being charged an overdraft fee).
BestCashCow believes that smaller banks that offer slower outbound or inbound ACH transfers can still make sense for the consumer. Assuming that you can prepare for transactions where there may be a day or two delay in moving your cash, the extra yield in a higher savings or CD rate may more than offset your loss of interest over that day or two. Often, this delay can be avoided by initiating the transfer at the recipient bank (although you will ordinarily be subject to a hold there too).
In the 21st Century, the ACH process is ordinarily completely free to the user for both outbound and incoming transfers. We strong encourage all consumers to avoid the few financial institutions, such as Salem Five Direct, that still charge for ACH transfers initiated through their websites.
Online banks offer some of the highest savings and money market rates in the banking world but many individuals are still nervous or skeptical about sending their money over the Internet. Yet today, opening an online savings account or money market account can not only get you a significantly higher rate, but it can come with more convenience and control than a traditional account offers.
The most often cited reason for opening an online savings account is that online banks can offer savings rates that are over 1% higher than those offline. Without the need to absorb the costs of branches and branch employees to support, they can operate more leanly, passing their savings on to their depositors. Even among online banks, there is a range of rates that reflects competing demands for deposit capital. Competition has become so keen that many major online banks offer their highest rates with minimal or no deposit requirements.
There are other very compelling reasons to move some of your money to an online-only bank. Principal among these are 24x7 access to your capital through a website or a mobile app and expanded customer service phone hours. In addition, some banks offer check writing and a debit card as part of their online account. Most however still find it most convenient to tie their online savings account or accounts to checking accounts at banks with large branch networks, holding only the minimum required at those banks and transferring capital back in as needed to cover expenses.
You can see all online savings account rates, balance requirements, and features on the here. In the reviews section of the table, users comment on their experience with a particular online bank, allowing you to ask questions and read about others experiences with account opening, customer service, transfers, and more.
Is Your Money Safe?
All of the online banks listed on BestCashCow are FDIC insured. While being FDIC insured is not a guarantee that a bank is necessarily financial sound, it indicates that the Federal Reserve guarantees your money up to $250,000 in each ownership category.
In addition, many of the highest paying online banks have been around for some time or are part of larger, better known parent organizations. Large, well known banks like Goldman Sachs Bank, Barclays Bank Delaware (one of the largest banks in the world), Emigrant Bank, Capital One, and TIAA CREF have rolled out online offerings with higher rates than their offline divisions.
Is it Convenient?
In general, with an online savings or money market account, you can access your money online all the time, and deposit and withdraw your money using electronic transfers. Some banks such as Ally now offer remote deposit though the mobile app. By connecting your online savings account to another account that you have at your main bank - usually a checking account - you can easily transfer money back and forth. An electronic transfer can take about 2-3 days to be complete, but at some banks, such as Goldman Sachs Bank, they are effected instantaneously. Banks often have a 5 to 10 day hold period during which money recently transferred electronically may not be withdrawn.
Customer Service
Almost all the online banks have phone numbers you can call if you have a problem. You can also send them contact them directly through their interface or by email.
Some Pitfalls
Some online banks have very high introductory rates for savings accounts. While the rate is guaranteed for a very period of time, it ordinarily is reduced to a lower rate shortly thereafter. Opening an online savings account at one of these banks can be viewed as being equivalent to opening a short term CD while having the money liquid. BestCashCow however recommends depositors avoid banks that engage in bait-and-switch tactics, and favor those online banks that have a history of remaining competitive and extending their best rates to their longest standing customers, as well as to their newest customers(Ally, Synchrony, Goldman Sachs).
Bottom Line
There are plenty of reasons to continue to do business with banks and credit unions with branch networks that are close to you. In fact, some of these banks offer savings and CD rates better than the most competitive rates online, so you should always check the rates in your area.
Often, however, the easiest way to gain an extra percentage point or more is to open an online savings account. They offer high rates, safety, and convenience to those willing to make the jump to cyberspace. When you consider the value of compounding even an extra one percent annually, your money can really add up over time (see the BestCashCow compound interest calculator here to calculate how much more you could make).
Do you plan to open an online savings account soon? If not tell us why by commenting below this article.
Anyone planning for their future – including you – is well served to try to set aside some of the resources that you earn today for tomorrow. At BestCashCow, we do not believe that there is anything to be gained by living an unnecessarily frugal lifestyle like many other websites advocate. Life is short, and living a frugal lifestyle is silly! But, we do believe that there are plenty of easy ways to save for the future, without going overboard. Here are 20 of our favorites:
1. Put your savings in a high interest savings account.
The trillions of dollars that Americans lose every year by keeping their money in a low interest savings account is just startling. The most amazing thing is that it can easily be avoided if everyone would just check the best online savings rates here. If you have never opened an online savings account, you should read this article to get started. If you are still not comfortable with online banking, you can still make more by carefully choosing between and among local banks or credit unions. This is the easiest and simplest thing you can do to put more money in your pocket if you have any savings. Bookmark these pages and be sure to check back often as rates are going up!
2. Set a plan to pay off all of your high interest debt.
You cannot even begin to save if you are one of the millions of Americans who carries high interest debt. Make a list of your high interest debts and then develop a strategy for paying them off. If you don’t have the resources available immediately to lower your debt right away, consider consolidating it in a home equity line of credit or a home equity loan.
3. Challenge every recurring expense.
Challenge every recurring expense you have. Consider whether you really need all of your cable channels and other services you may be paying for monthly. Many people have been paying for a service so long that it becomes second nature, but that doesn’t mean that you shouldn’t cut it out. Challenge yourself by writing down every recurring expense you have, then look for expenses you can fully cut out, and then find ways to save money on the remaining expenses.
Insurance rates – for health insurance, home and auto insurance and life insurance - are always changing. New competitors enter markets and others change their offerings (becoming more competitive or less competitive). Review all of your policies annually and make sure that they are the best for you. The cheapest isn’t always the best, but you may find the same or better coverage for less money when you shop around.
5. Make a practice of delaying large purchases.
When you’re considering making a large purchase, refrain from buying it right away. Rather, spend some time researching the product, and commit not to buying it until some time – such as one month - has passed. When you are less spontaneous, you end up only with the things that you really need and really want.
6. Wait until the end of the month or quarter to make your largest purchases.
All sales reps have quotas to meet per month or quarter, so if you wait until the end of the month to make a big purchase, you can potentially save a lot. Car salespeople especially work with quarterly quotas and buyers can score the best deals if they can wait until the end of the quarter.
7. Use electronic coupons where possible for things you need.
In general, physical coupons aren’t worth the time you spend accumulating and managing them. However, you should be on the lookout for electronic coupons that save you a lot of money on things you need anyway.
8. Take advantage of loyalty programs offered by the travel industry.
My loyalty programs for Delta, United and American Airlines over the years have subsidized all of my personal travel for decades (including many trips to Hawaii, Europe and Asia). My loyalty to Starwood and Hyatt has been equally rewarded. Take advantage of these programs. You can boost your balance in these programs with the right credit cards.
Your habits - good and bad – always work against you when you are trying to save money. Alcohol and smoking are obviously bad habits that are very costly (the cost of these habits should not be your main reason to quit). Vitamins, supplements and other so-called nutritional aides may seem like good habits, but they are, in fact, expensive habits designed to separate you from your money. Try eating well instead.
10. Reduce costs of your other habits (Brew your own coffee)
My most expensive habit is coffee and I can’t kick it, so I brew my own. Instead of spending $4 per cup at Starbucks or a real coffee shop, brewing my own coffee keeps the expense below 15 cents a cup.
11. Drink more tap water.
Water is better for your health and saves you a lot of money. Tap water is not only basically free, but it helps save the environment. Invest in a water filter for your home. The savings are especially great when you drink tap water instead of soda or beer when dining out (at least this works in New York City where the tap water is safe to drink even when it hasn’t been filtered).
12. Eat at home.
Eating at home is easier and healthier than eating out. It is also much cheaper. I routinely throw together a quick salad with all sorts of great and exotic fruits and vegetables from my local Whole Foods that I won’t find on any restaurant menu. If salads aren’t for you, try stir-frying or make homemade pizza with a ready-made bobboli crust.
13. Get paid to spend.
Maximize your credit card rewards by using the right card for your purchase. It is BestCashCow’s view that the most value can be extracted from travel rewards credit cards. Find the best travel rewards sign-up bonuses here and the best cards for your spend here. Those who don’t travel may prefer cash-back cards. Whichever you prefer, always be on the lookout for cards that might have multiples of the regular reward rate in certain categories.
14. Build your credit.
Whether you have good credit, fair credit, or bad credit, work on building it up. Your credit determines your eligibility for mortgages and home equity loans. It determines whether you can get the best credit cards. Potential employers will also routinely run credit checks on job applicants.
15. Save energy.
This one sounds so simple, yet is so often ignored by so many. Turn off the lights and the air conditioner when you aren’t around! Stop wasting energy. Preserve your resources as well as the earth’s. Maybe even adjust downward the brightness on your TV and computer screen.
16. Buy in bulk and buy generic when possible.
Costco can save you a ton. But, also think about name brand household products that carry the same ingredients as generic brands. Generics can often taste better or be healthier too. You can save thousands of dollars by simply buying the generic store brand instead of the well-known brand. Kirkland is Costco’s own generic brand.
17. Cancel catalogs and unsubscribe from email announcements from companies trying to sell you stuff.
Announcements of sales or cool new products make it very tempting to buy something you don’t need. Instead, stop the catalogs and emails from ever getting to you in the first place, and you will save time, money and the environment.
18. Exercise.
This is, in many ways, the most important piece of advice we can possibly give. Staying healthy is the best way to avoid costly medical bills later. Biking is also often the cheapest and fastest way to get around. Ask a Dutch person.
19. Clean Out Your Closets.
By getting rid of all the excess stuff in your home, you will make your life simpler and more peaceful. Let others benefit from stuff you don’t need any longer or that your kids have outgrown by giving it away.
20. Find happiness in life, not spending.
Psychologists have proven that people buy stuff because they subconsciously believe that it will bring them happiness. While you may really need an Iphone X, do you really need the iWatch and the latest Audi with Apple Carplay? This stuff will only make you happy for a day or two and then you will have buyer’s remorse. Try to find joy in nature, in exercise and in each other, instead of trying to get a kick from unnecessary purchases.
Now you’ve got 20 ways to save money. We hope you’ve read something here that will help with your finances and help you live a happier life.
Expert Reviews of Well-Known Online Banks, November 2026
Online Savings - 3.50% APY, $1 minimum
Great for: Competitive CD Rates with no transaction fees.
Overview: Marcus is the online bank of Goldman Sachs. Throughout 2018, it consistently offered one of the highest online savings rates, but it was quick to lower its savings and CD rates in 2019 and 2020 and has lacked competitiveness since then. Marcus has a highly rated mobile app.
Highlights: Marcus is very highly rated in customer reviews on BestCashCow. Users cite lightening fast ACH transfers, the ease of web access, strong customer service and the absence of any fees ever, including inbound or outbound wire transfer fees. The bank sometimes offers better rates to those who successfully push the bank on their contacts (i.e. receive a better rate if you get someone to sign up).
What to watch for: Marcus has been lowering its rates so that they are no longer competitive. No ATM access. No custodial or trust accounts.
Goldman Sachs Marcus's Climate Grade: B - Goldman Sachs continues to be a major financier to the oil and gas industry but has taken a leading role in financing major renewable energy projects.
Online Savings – 2.80% APY, $1 minimum
Great For: High Savings and CD Rates with no transaction fees ever.
Overview: In the online space, Citizens is a decade old player that was previously branded as Citizens Access. It brings the experience of Citizens Bank N.A., one the largest, oldest and most well established US banking institutions.
Highlights: Citizens never charges any monthly fees. Its user reviews on BestCashCow have been outstanding. It was ahead of the curve in increasing its savings rates in anticipation of each Federal funds rate increase in 2018, and was consistently more competitive than other well-known banks during the 2022/2023 rate increase cycle. Citizens also allows online customers to set up online savings and CD accounts in the name of a personal trust (very rare among online banks).
What to watch for: Users reviews in 2022 frequently cited online access issues, but we understand those to have been resolved in 2023.
Citizens' Climate Grade: A - Citizens has made real strides in lending to renewables projects, has lent to several Ørsted projects, and has an extensive plan for its lending to sustainable energy projects.
Online Savings Account – 3.20% APY, no minimum
Great For: Sometimes competitive savings rates and No Penalty CD rates with 24/7 Customer Service.
Overview: Ally’s advertising campaigns in the years since rebranding from GMAC Bank have made it one of the most recognized online banks. It savings rate has a history of being competitive, but has trailed other well know banks since 2023. The bank also offers competitive CD products (with modest early withdrawal penalties) and no penalty CDs (with no early withdrawal penalties).
Highlights: BestCashCow user reviews cite a strong mobile app and the ease of getting into and out of No Penalty CD products. Ally often offers new and existing users a 1% cash promotion for bringing new deposits, and regularly gives existing depositors a 5 basis point step up for renewing CDs and No Penalty CDs.
What to watch for: While Ally advertising campaigns in the 2010s were based around the principle of treating every customer the same, Ally now alternates between offering a higher rate in its savings account and its money market account. Customers need to pay attention to which account is more competitive at any given moment and move their money between the two accounts - or Ally's No Penalty CD - accordingly. Additionally, Ally is the former GMAC Bank, having been spun out following the 2009 financial crisis, and may continue to have significant exposure to used automobile loans. In addition, Ally's reviews are no longer universally great. Some customers complain about waiting hours to reach customer service by phone at all hours of the day. Others have expressed frustration about being inundated by Ally's cross-selling of auto loan, personal loan, credit card and online trading products.
Ally's Climate Grade: B - Ally has an extensive Corporate Social Responsibility report and claims that it is not directly funding harmful fossil fuel emissions projects. It however is the former GMAC and should be able to take an aggressive roll in reducing funding for internal combustion vehicles in favor of electric ones.
High Yield Savings – 3.75% APY, no minimum
Great For: Stronger CD rates than many other well-known online banks.
Overview: Synchrony Bank is the former GE Capital Retail Bank that has been spun off completely into its own institution. Even though Synchrony is an entirely independent entity now and should not have exposure to GE's troubles, there may still be hidden exposure and depositors should remain well within FDIC insurance limits.
Highlights: Online savings accounts can be opened for IRAs and trust accounts (which is ordinarily not possible at leading online banks). Upon setting up an account, you may also add up to 10 beneficiaries. Your account may be linked with up to 10 external accounts at other banks. Synchrony offers ATM access and will reimburse up to $5 per statement cycle in other banks' ATM fees.
What to watch for: Synchrony Bank is associated with worse customer service than most other well recognized US online banks. Their website continues to lack basic functionality about deposit times, processes and limits, and has no web-based customer service functionality (no internal email, messaging or chat functionality). To boot, User reviews cite the inability to reach US-based customer service reps by phone. During periods where the bank is not rate competitive, it will cancel outbound transfers with no notice, limit them to $25,000 per day, and/or add further delays to its transfer process (beyond the usual 3 business days). The bank also charges a $25 outbound wire transfer fee.
Synchrony's Climate Grade: B - Synchrony has no climate initiatives but no known lending to carbon producing industries.
Tiered Savings Account - 3.50% APY, no minimum
Good for: Solid APY with No Minimum Balance
Overview: Barclays Bank Delaware is a division of the often-troubled UK-based Barclays PLC. In the US, its brand recognition emanates from its acquisition of Lehman Brothers in 2008, its name on an arena in Brooklyn and its role as one of the credit card issuers for American Airlines. Unlike in the UK, its US commercial banking operation does not have a branch network and operates mainly online.
Highlights: Barclays offers savings accounts with no minimum to open, 24/7 access to funds, online transfers to and from other banks, easy ACH transfers, direct deposit and a mobile app. Barclays' user reviews are generally very positive.
What to watch for: Barclays Bank Delaware is not consistently competitive in raising its savings rates as the Federal Reserve increases the Fed funds rates. With uncertainty around the UK's economy under Prime Minister Rishi Sunak, BestCashCow strongly recommends that depositors at this U.S. subsidiary maintain deposits strictly within FDIC limits.
Barclays' Climate Grade: D - Barclays is one of the world's biggest lender to the oil and gas industry, and has no known lending to major renewable energy projects.
 Written by
 Edited by